4 Compounding Machines To Buy Now
These notes were generated by AI and may contain inaccuracies.
Welcome back everyone. Today on the Joseph Carlson show, there are thousands of companies in the stock market and in this episode we'll be going over four of them. Four companies that are buys today. The companies we're going to be going over are compounding machines. They're very strong companies and they're offering you an entry point today. We also have other news we'll be going over, including Netflix now adjusting their deal to buy Warner Brothers Discovery. Before they were doing it in part cash and part stock. Now they're likely adjusting it to all cash. We'll be looking at the real reason they're doing this. We also have the news that Trump is demanding credit card companies have a capped interest rate of 10%. This has caused a stir in the market. It's caused many companies from banks to credit card companies to sell down. There are so many misconceptions, bad information, and outright lies associated with this news, and we'll be clearing it all up in this episode. We have Google continuing from strength to strength. We'll be looking at how Google's Gemini has a significant advantage over competitors. And then finally, we have one of the weirdest stories in this version of Fail of the Week. We have Matthew McConaughey trademarking himself. He's made a trademark of himself to fight AI misuse. We'll be looking at the full details of what exactly he's trademarking and how this helps protect him from AI abuse. So, we have a ton to get to in this episode, and if you haven't already, go to qualum.com and try out a free trial. It is the best stock analysis platform. Qualum has charts and graphs that are easy to use and easy to visualize. Qualum has news of recent events catching you up to speed on what's happening with every company in your portfolio. Qualum has an advanced watch list with a dip finder feature that shows you which of your companies are in a dip and which ones are in a price surge. Qualum has summarized earnings call transcripts by topic to make it easy to browse what's going on with a company. It also has a DCF calculator that's super easy to use, a portfolio analysis tool, and more. Try it out risk-free at qualum.com.
Now, as we jump into today, you'll notice that my stock brokerage account is lower than it was just a day ago. It's quite a bit lower. In fact, we're down around $10 to $15,000 just on the day. I was actually getting near $1 million. We were only $7,000 away from a million. Now, we're $32,000 away. Just today, as of right now, we are down $10,000. If I move to the story fund, you see the same thing. If I look at the past day, we are down $7,400. And this isn't just one company. A lot of companies are selling off today. Meta, Google, Nvidia, Apple, Microsoft, all the big tech companies, all the NASDAQ leaders, all the AI winners, plus even software companies. Intuit's down big on the day. Salesforce is moving down a little bit today. Adobe just hit a 52-week low. There's no love for Duolingo in this market. It continues to trade down. Companies big and small today are getting crushed in this market. The Dow Jones is down. The S&P 500 is down even more. And down the most is the Nasdaq. The biggest winners are leading the losses today. So, if you're looking at your portfolio today, it looks like a bloodbath. Many of your favorite stocks are probably selling down aggressively. And this is how investing works. This is exactly how it works. It's like Mike Tyson says, everyone has a plan until they're punched in the face. And if you have a plan with your investments, it's important to stick to that plan even though today we're getting punched in the face.
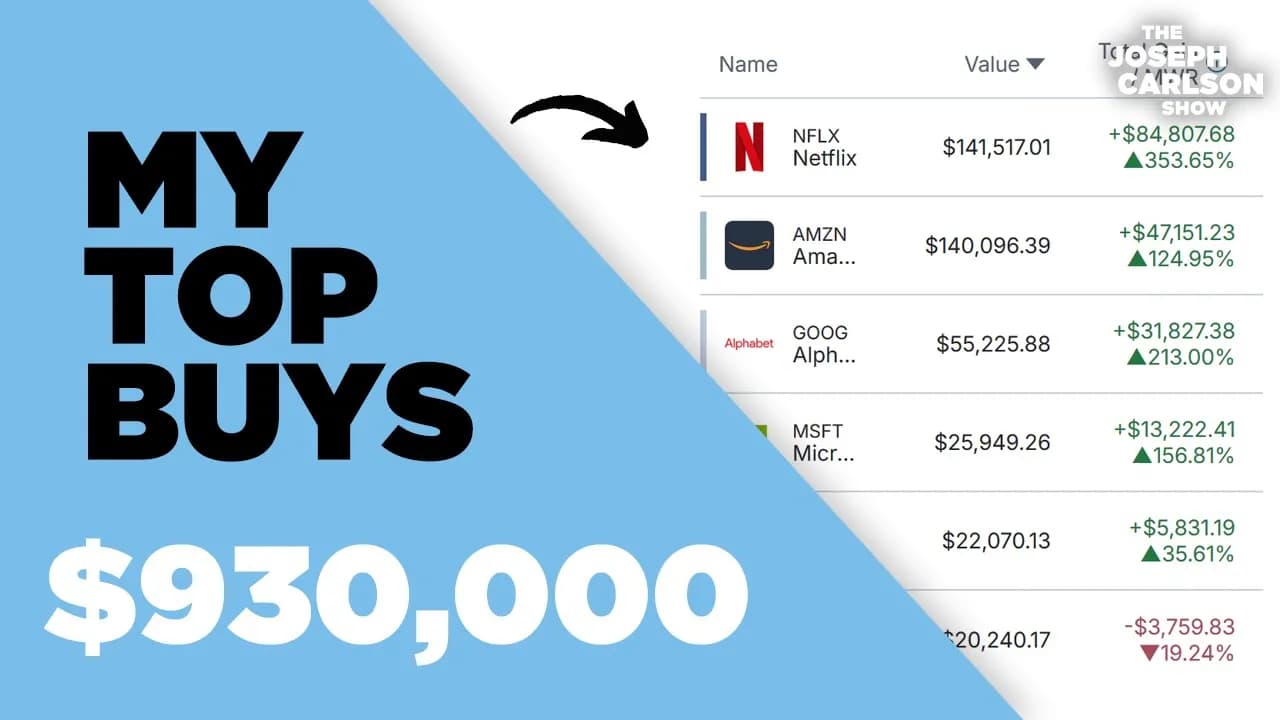
And when looking at both portfolios, when looking at the top companies to buy, four of them came to mind. The first one is Netflix. This is a company that I believe should be on the radar to be a purchase by any new investor. When we look at Netflix, there's a couple reasons that I outline this company. First of all, the price is way down from its recent highs. Netflix is going through a substantial dip. When I see a highquality compounding machine that recently traded at $133, it's now down to a price of $89. that catches my attention. I simply look at these situations and want to learn more about them. The news of any big acquisition will likely drag down the stock price of any company, and Netflix is no exception. But there's reason to believe that in this case, it's actually a benefit for Netflix. In the case of Warner Brothers Discovery, the acquisition makes sense. Warner Brothers Discovery represents highquality prestige TV series that have incredible IP value. Intellectual property is so valuable in the world of content and Netflix knows that. After all, much of what's watched on Netflix is licensed content from other companies, especially Warner Brothers Discovery. These are the series and movies that people love. Warner Brothers has an excellent box office business and they have an excellent streaming business. The problem with Warner Brothers Discovery is that when they were spun off from AT&T, they were dumped with an enormous amount of debt. So Warner Brothers Discovery ever since this point in Q4 of 2022 has had a staggering amount of debt and that weighs on you. The interest expense of this debt weighs on you. Even with this huge amount of debt they've spent the past years paying it down every single quarter, quarter after quarter. Now while they're busy paying it down, they can't do things like invest in new shows. They can't expand their business. They can't expand in talent and technology. They're too busy paying down debt. And this is where I want to highlight an important distinction. The content of Warner Brothers Discovery in the actual business in terms of their assets and their production is excellent. It is top tier content and everyone that has access to the library knows that the financials, their current market structure is really bad. They have an enormous amount of debt that is causing them years of continual debt management. The reason that the Netflix acquisition makes so much sense is because Netflix will get the IP. They'll get the incredible content that'll really help out Netflix's library for the long term, and it also solves the problem of their bad financial structure. Netflix has the financial strength to pay for this acquisition and the debt very easily. This will not be something that holds down the company from reinvesting back into the future. So, I look at this as a situation where Netflix is solving the biggest problem with Warner Brothers Discovery, which is the financial situation while obtaining that incredibly valuable IP from their library. Netflix knows this and they want this deal badly. They already have a signed agreement and they're trying to protect themselves from the ongoing attempts from Paramount to block their deal or obstruct their deal or make it so that Netflix can't buy Warner Brothers Discovery. And Netflix is making moves to preempt this. David Faber on CNBC explains this fully.
The vote is the key. It was not going to take place until the late spring or early summer. That will change should Netflix move forward with a change to all cash. Why? Well, when you issue stock, you've got to issue a lot more financials, a lot of accounting around it. And that just takes a lot of time, a lot of time, a lot of effort, work, not to mention expense even uh for doing that. This makes it cleaner and quicker. How much quicker? A lot. We're talking months. In fact, again, uh unclear, but you could see a shareholder vote as soon as late February, early March. If in fact Netflix does this, you will get the proxy and you will get the date, but perhaps the proxy will come very soon. Again, that's the point I'm making here. The proxy itself would not be filed for quite some time if you were continuing to include stock uh in the transaction. that will change with an allcash offer and that will bring the question as to whether Paramount is going to raise and some and do something beyond suing and claiming it's being treated unfairly um in order to try to win the day. That remains unclear at this point, but Sarah will have the effect of consolidating that timeline significantly.
By moving from having their deal in part cash and part equity to straight cash, it clarifies the deal. It makes it simpler and most importantly, it pushes the timeline forward for Netflix getting a vote on this by months. So, Netflix is moving fast to close this deal down fast. The takeaway here is that Netflix is being aggressive in pursuing this deal. They know that Paramount is nipping at their heels. They're doing everything they can to steal Warner Brothers Discovery from them, and Netflix is not going to let that happen. But where does that leave us as Netflix investors? This has been a company that I have in the portfolio. I already have a decent holding in it and the stock doesn't seem to like this. In fact, investors seem to be selling out based on this news. I think investors in Wall Street have this wrong. Netflix should not be selling down on this news for a simple reason. Usually, stocks sell down because they're becoming structurally weaker. For example, Salesforce is selling down over the past couple of months because the stock is becoming structurally weaker with advancements in AI and coding. There's lots of other tools that are putting pressure on Salesforce, making it so that this company has to contend with all different types of competitors. Adobe selling down and multiples are contracting because the company's becoming structurally weaker in the competitive landscape. They're now having to deal with the likes of Figma and the likes of Canva. Big competitors that are taking market share on the low-end consumer and on the design consumer. Adobe's in a structurally weaker position than it was a year ago. By contrast, Netflix's stock is selling down as the company's becoming structurally stronger. With the acquisition of Warner Brothers Discovery, Netflix has simply won the game. There's no coming back from that. There's no alternatives. Netflix would have such a massive library that it would be indisputable. Can you even imagine the content that Netflix would have? Their production capacity would be unmatched. Netflix's streaming library would be unmatched. Their utility and ability to cross-sell different pieces of content to different consumers of all varying tastes would be unmatched. Netflix is already the strongest media company in the world, and this would only increase their power and make them stronger. So, we have a company that's going down in stock price as it's becoming structurally stronger. Now, many of you may say, well, look, Disney bought a different company and look how that's worked out for Disney. That's true. Disney's a big media company and you may see some comparisons from the Walt Disney Company to Netflix. The difference with these comparisons is that the thing weighing down on Disney is not their streaming assets. It's not Fox. It's not Disney Plus. What's weighing down on Disney is their declining cable TV business. Without that, Disney would be a compounding machine. By contrast, Netflix is not buying any cable TV assets from Warner Brothers Discovery. They're only buying Warner Bros. They're not buying Discovery. So, Netflix is getting just the good parts without getting any of the bad parts. This puts them in the strongest position possible. This makes competition even harder against Netflix. It strengthens their business without diluting it into secular declining businesses like cable TV. When I look at Netflix today, I see a company that's declining in stock price because of short-term concerns, because of commotion, because investors think it's a dead stock for the next year. But in reality, this is a company that's moving step by step aggressively into a much stronger position in the media landscape. I think that Netflix is a buy today right now. But I want to warn investors that this is a highly volatile company and this could go much lower. I could see on the low end, in fact, I could really see it happen where Netflix trades all the way down to around $70 per share. I think that's where we get to around the lowest end. The upside, by contrast, is very big for Netflix over the next 5 to 10 years. If they secure the deal with Warner Brothers Discovery, if they get all the debt under control, which they will, and if they leverage their content at the scale of Netflix, we can see really big things from this company over the next 10 to 20 years. I see it multiples higher than what it is today.
The second stock that is a buy today is JP Morgan Chase. And this is one that I haven't covered recently, but it's actually a company that I used to have in my portfolio. And it's a company that I made solid gains on in a short amount of time. I bought it during the COVID lows. I held it for a couple years and sold it for around a $15,000 gain. Like you'll hear many investors say, I wish I never sold the company because it's much higher today than it was then. The stock price has over doubled from $150 to around $350 now, but it's recently gone through a small pullback. Now, it might be surprising that I highlight JP Morgan as a buy seeing that this is a bank. And banks are typically not companies that I buy because they're looked at as more cyclical, less dependable. They are also black boxes. They're more difficult to understand. And that's traditionally what banks have been. But over the past 5 years, banks have really evolved and a couple things have changed dramatically under the hood of what's going on with JP Morgan Chase. The transition that's happened is that companies like JP Morgan, the largest banks in America, are looking more and more like tech companies. In fact, they don't really look like the traditional bank that takes in deposits and makes loans to make money. That's historically what banks have done. But instead, JP Morgan can now be looked at as more of a platform business that uses its banking charter to have an unfair advantage over traditional tech companies. And this is the same thing that Tom Lee has been arguing with the financials for some time. That investors are looking at them in an antiquated way that they're simply banks taking in deposits and lending money. But that's not the business model of these banks today. Financial services companies are really big beneficiaries of AI and they're big beneficiaries of using blockchain technology. Both will allow them to reduce their employee intensity of their business. And so I think the large tech forward banks are going to start to see margin expansion and trade more like tech stocks in the future.
And that's why you know the JP Morgans and the Goldman's could actually be the next mag 7. They are looking more and more like tech companies every single day.
Part of what JP Morgan does is they take in deposits, they lend out money just like any other bank, and that does make up a big portion of their revenue. But there's also a lot of other aspects to what this company's doing and how they're earning real revenue. Inside the consumer segment of JP Morgan, the Sapphire credit card makes them around $29 billion annually. You have interchange fees. You have annual fees on their high-end cards. These are more tech-like services than banking services. You have another huge segment of this $20 billion per year that they're earning through wholesale payments. This is very similar to the business model of Stripe. They're basically processing payments. They earn an enormous amount of money from doing that. And Stripe as we look at it is not a bank company. It's a tech company. But JP Morgan has this type of business built into it making up a significant portion of revenue. Then on top of those massive segments of their consumer cards, their branches, their stripe like business, they also have wealth management services where JP Morgan handles money for super wealthy clients as well as many institutions. And then they also have commercial banking where of course they give big loans to big businesses. They help different businesses go public. They help different businesses with all financial situations. The mix of revenue from JP Morgan has looked more and more tech-like every single year. It's a higher quality revenue mix. And like Tom Lee says, as the company becomes higher margin, so should the valuation expand. When we look at the valuation of JP Morgan, there's also a couple things I want to point out here. If we look at a traditional bank, the way that you would value a traditional bank is by the price to book. And typically, you'd look at a traditional bank and say that JP Morgan is rather expensive. It's trading at a price to book value of 2.3 times. That's much more than most banks that trade at 1.5 times or 1 times. So by the traditional bank metric, JP Morgan is expensive. But then if you value it the way that Tom Lee is, looking at it from a tech perspective, you would value it by PE ratios, which is what we commonly use for tech companies. And if you're valuing the company by its price to earnings, it looks rather cheap. trading in the low teens, the mid-teens, a 14.5 forward PE ratio. That is very cheap when comparing to almost any tech company. So whether you're valuing the company based on its PE or its price to book is determined by whether or not you're an investor valuing it based on a traditional bank metric or a tech multiple. And it's one worth considering to any investor that wants to have access to a massively profitable tech-like bank.
Now, the third one worth buying today is Amazon. This is one that's been on my buy list for some time and it's also a large holding in the portfolio. There's a lot of different reasons to buy Amazon, including their growing advertising business, their mix shift of higher quality revenues over time. You can see that Amazon continually is growing in their thirdparty seller services, their advertising subscriptions, and AWS. But out of all of these reasons, I want to highlight two that I believe are the single biggest reasons to own Amazon today. The first one's Amazon Web Services, AWS. My thesis with Amazon is that AWS will continue to accelerate. I believe it will grow 18 to 19% over the next year and that accelerated growth will continue to push the stock higher. When we look at the customer commitments to AWS, those are growing faster than their current growth rate. We have 22% growth in customer commitments, which means that more people are signing up and signing contracts to use AWS in the future. The operating margins of it are also very high, 35%. This is much higher than where Google's are or even Azure's. This is incredibly high margins and they should go higher. But the other reason that I highlight Amazon as a buy today is because I think overall when we can break down all the various things that Amazon's doing, it has so many different touch points to people's lives every single day. But one of the big stories hiding behind the numbers is the automation. Amazon is a company that has an enormous amount of revenue but very low margins overall because so much of their revenue is in retail businesses. This requires a lot of leg work, a lot of manual labor. Amazon employs roughly 1.5 million employees. That's a lot of employees. They're one of the biggest employers in the world. As automation continues to advance rapidly over the next 5 to 10 years, as robotics take on more of the leg work, the manual labor that many human workers are doing today, Amazon should be able to move faster, be able to ship packages better, have fewer complaints, fewer errors. They can also have fewer employees. Amazon can continue to grow the revenue while keeping the employee count flat, which creates operating leverage and increased margins. Not only does it have fewer employees, but it has fewer work time off, fewer lawsuits, fewer employees being hurt on the job, fewer health insurance claims and bathroom breaks and so on. Employees are expensive for companies. Amazon has an enormous amount of employees. And having robotics be such a massive tailwind for this company, I believe, is something that investors will be very attracted to over the upcoming years. Amazon today is worth over $300 per share, but it continually trades at around 230 to 240. Now, it is going up in stock price and I believe that it will continue to over the upcoming year, but I believe investors have a very attractive entry point here today.
In number four, we have Mastercard and for this one, I'll group it in with Visa. Both of these companies are under pressure recently as there is a new Trump social tweet where he said that he's interested in capping credit card interest rates at 10%. And this has caused a huge stir in the markets, not just for banks like JP Morgan, but also for Visa and Mastercard. Now, there's a lot of misconceptions about how Mastercard's business actually works. For one, Mastercard doesn't earn money on interest payments. So, when you're paying your credit card bill and you're paying interest for late payments, Mastercard isn't making money from that. They only make a small amount of money every time you swipe the card. Mastercard is a tech company. They're not a lender. They are a network focused on speed of transaction, connecting customers with merchants and banks, and making sure the transaction goes through with fraud protection, with insurance, and with knowing who you're buying from and knowing who you're selling to. That is Mastercard's business. Mastercard and Visa are not in the business of lending money. Now, after Trump posted this, there was a huge buzz of news regarding it, and many people jumped on board. One of them was Senator Elizabeth Warren, who has proposed this for a long time. We also have other people even across the aisle like Josh Hawley that also support this and there's other notable Democrats like AOC that support this as well. So there is a number of people in the Senate that do support this but that number is limited and that's what brings me to why I believe this company's a buy today. The concerns over a 10% credit card cap, I believe, are very misfounded. And I think the chances of this actually passing with a hard cap of 10% interest on credit cards is incredibly unlikely. The biggest problem with trying to make this work is what would happen in every case if companies like Visa, Mastercard can't have any cards with over 10% annual percentage interest rate, then you would have them not being able to lend to almost everyone that is sub 700 credit score. So if you have below a 700 credit score, your credit card is gone. It's toast. There's no chance you're getting a line of credit. When you look at the outcome of this, do you think that your senator and your congressperson wants to be responsible for you losing access to credit, you not having your credit card anymore, you having to turn to loan sharks and buy now pay later applications, do they want to be responsible for you losing access to something you enjoy using? No. On top of that, the other consequence of this is that credit card rewards for high income earners, meaning people that have above a 700 credit, people that have stable incomes, people that pay their bills on time, their rewards would go down. So, this is a double whammy. Not only would a massive amount of people, millions of people would lose access to credit, but the people that earn rewards would also earn less rewards. So people above 700 credit and people below 700 credit would be harmed by this bill passing. Moderate Democrats do not want people to lose access to credit. They don't want to be responsible for millions of their constituents not having credit cards that they enjoyed using. And moderate Republicans don't like price controls from the central government. Moderate Republicans like free markets. They like competition. And in both parties, neither of them want to be looked at as the person that took away your access to a credit card. The House Speaker, Mike Johnson, already seems to realize the blowback that this would cause, the unintended effects. He says, quote,
You got to be very careful if you go forward in that. And our zeal to bring down costs. You don't want to have negative secondary effects of that. They would just stop lending money. And maybe they cap people on what they're able to borrow at very low amounts.
Mike Johnson is being very careful with what he's saying. He's trying to balance not offending Trump, but he's also trying to point out that look, there are some big things we have to be concerned about here. And he's already highlighting some of these structural challenges. And Mike Johnson is exactly right here. If they go forward through this, millions of people will lose credit cards, credit
Credit reward points will go down, and credit limits will go down substantially. This could negatively affect consumers and the economy. The digital economy drives stock market performance and company earnings growth because people transact easily with less friction. Restricting this slows transactions. Regulation is incredibly unlikely to pass. As a Mastercard shareholder already bullish on the company, buy when the stock trades down due to political bickering or posturing from the president. Mastercard and Visa are becoming structurally and strategically more important. Mastercard has business growing outside its normal rails business. With the stock at 5-year low multiples, it's time to buy.
Google has an unfair advantage: Gemini AI uses personal data from Gmail, Search, and YouTube for personalized answers. Example: Needed new tires for a 2019 Honda minivan two weeks ago. Standing in line at the shop, didn't know tire size. Asked Gemini, which found specs, suggested options—one for daily driving, another for all-weather—referencing a family road trip to Oklahoma from Google Photos. Pulled ratings and prices. Then needed license plate; Gemini pulled the seven-digit number from a Photos picture and identified van spec trims from Gmail. Google's leveraging photos, YouTube history, Gmail for uniquely personalized answers no one else can match, including ChatGPT.
This personalization is hard for anyone to compete with. ChatGPT lacks this data. Massive leverage over ChatGPT. Apple should do this with iPhone data but lacks AI models, so partners with Google. Google wins with Apple. Over the past year, Google went from no answer to ChatGPT, a sluggish app falling behind, to catching up with structural positioning via personal data for better user handling than ChatGPT.
Matthew McConaughey trademarks himself to fight unauthorized AI fakes. Over past several months, Interstellar and Magic Mike star has eight US Patent and Trademark Office-approved applications featuring himself. Attorney: Trademarks stop AI apps or users from simulating his voice or likeness without permission, a growing concern for performers.
This is defendable; he should own his likeness. Fail is AI making life harder: pranks more disruptive, stealing voice/likeness/image without compensation. You should own yourself—voice, likeness. He shouldn't need trademarks; it should be common law.
Trademarks include him standing on a porch, 3-second clip sitting in front of Christmas tree, audio saying "All right, all right, all right" from 1993 Dazed and Confused. McConaughey: "My team and I want to know when my voice and likeness is ever used. It's because I signed off on it."
Not targeting anyone specific; preempting trend. Lawyers: Likeness may or may not be manipulated, but trademarks usable broadly against unauthorized duplications. In AI misuse scramble, this tool stops violators and takes them to federal court. 100% agree; failing that people must copyright their own image, which they should already own without permission to manipulate/copy/duplicate.
Keep Joseph Carlson in your library
Save the videos and channels worth coming back to, and find them again in one place.