6 Brutal Money Stats of the Average American (2026)
In a Nutshell
The average American earns $52k before taxes but takes home only $3k monthly after deductions—barely enough to cover housing, transportation, and food—while saving just 3-5% of income and carrying $9k in credit card debt at 24% interest. Median retirement savings of $65k yields only $293 monthly under the 4% rule, leaving most dependent on Social Security, with 25% having zero saved. The core message is that average financial habits create a fragile baseline; individuals must save more, eliminate high-interest debt first, and invest in assets early to preserve purchasing power and achieve stability.
These notes were generated by AI and may contain inaccuracies.
A person working 39 years and retiring with the median retirement balance for Americans 65 and older would receive only $293 per month using the standard 4% withdrawal rule applied to $88,000. This figure represents the median, not the average.
According to the Bureau of Labor Statistics, the median full-time worker earns just over $1,000 per week, equaling approximately $52,000 annually before taxes. This represents individual income, not household income. After federal taxes, state taxes, Social Security, and Medicare deductions, take-home pay ranges between $35,000 and $40,000 annually depending on location, resulting in roughly $3,000 monthly.
The speaker recommends earning at least $75,000 annually to comfortably invest, noting that perspective on whether this amount is substantial depends on individual spending habits.
The Bureau of Labor Statistics reports average American household spending at $6,545 monthly or $78,500 annually. Major expense categories include:
- Housing: $2,189 monthly ($26,000+ annually)
- Transportation: $1,110 monthly (over $13,000 annually for car payments, insurance, gas, and maintenance)
- Food: approximately $800 monthly
These three categories alone total over $4,100 monthly before accounting for healthcare, clothing, subscriptions, entertainment, or vacations. A single median earner with $3,000 monthly take-home pay faces a shortfall on these three line items alone.
The average FICO score in America is 715, falling in the good range on the 300-850 scale. However, the average household carries $9,000 in credit card debt. At 24% interest, this generates over $2,160 annually in interest payments alone, before any principal reduction.
The speaker advises paying off credit card debt before investing in the stock market, as the guaranteed 24% return from debt elimination exceeds typical market returns of approximately 7% annually.
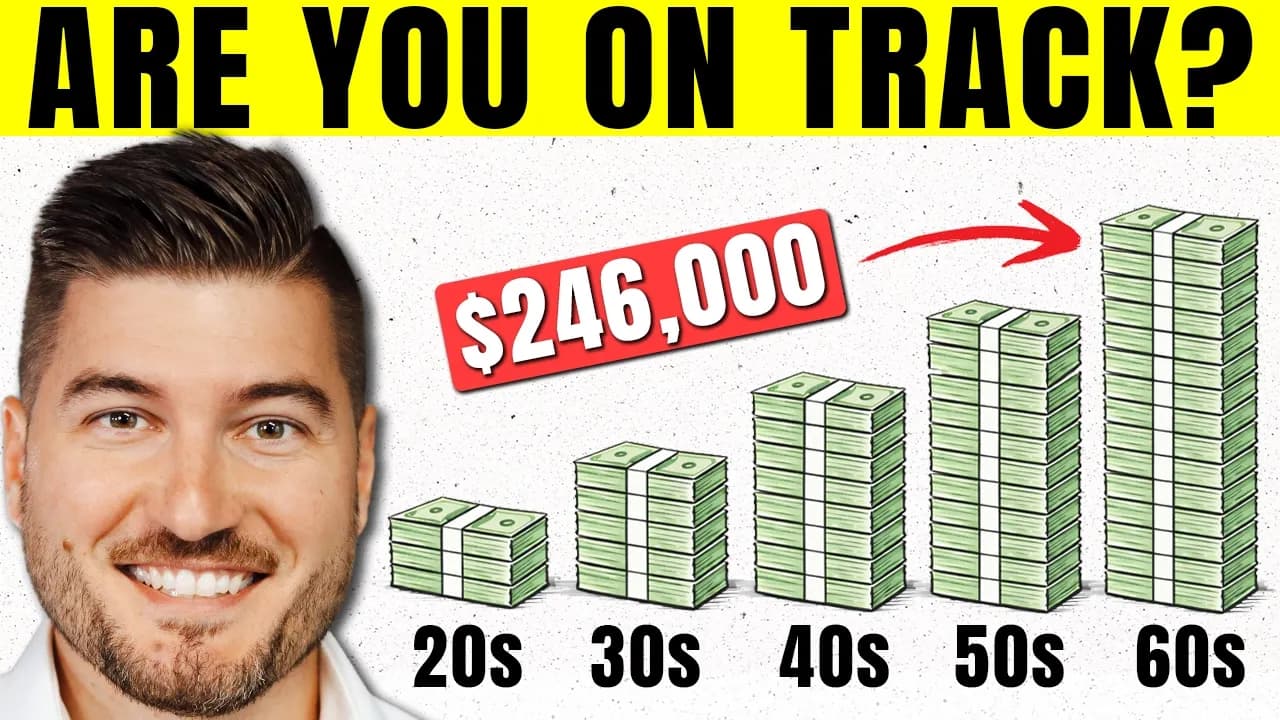
Net worth represents the single most important financial metric. Calculate it by subtracting total liabilities from total assets. According to Federal Reserve data, the median American household net worth is $192,700. Excluding home equity, this median drops below $60,000.
Age-based median net worth figures:
- Under 35: $39,000
- 35-44: $135,000
- 45-54: $247,000
- 55-64: $364,000
- 65+: $49,000
Much of middle-wealth household net worth consists of home equity with limited liquidity. Liquidity refers to assets that can be quickly converted to cash, such as stocks or bank deposits, versus real estate which may take months or years to sell.
Federal Reserve data shows the median American has $65,000 saved for retirement across all ages. Age-specific retirement savings:
- Under 25: $2,000
- 25-34: $14,000
- 65+: $88,000
Applying the 4% withdrawal rule to $88,000 yields $293 monthly. Combined with average Social Security of $2,071 monthly, total retirement income reaches approximately $2,364 monthly. Twenty-five percent of Americans have zero dollars saved for retirement.
The speaker notes that grandparents who returned to Europe after working in America experienced significantly higher quality of life due to lower costs. Future generations may face delayed Social Security eligibility, potentially starting at age 85.
The Bureau of Economic Analysis reports Americans save roughly 5% of after-tax income, though the speaker cites closer to 3-4% in previous analysis. Financial planners recommend saving 10-15% specifically for retirement, separate from other goals like home down payments.
The average American stops working at age 61, creating a gap before full Social Security benefits begin at 67. Someone reaching 65 can expect to live another 19-21 years, meaning retirement at 61 requires funding approximately 25 years.
Successful individuals save more than the average 3-4% rate and begin earlier. The speaker advocates investing in assets rather than cash, stating that asset holders benefit in inflationary environments. The advice emphasizes that money is created through monetary policy, making preservation of purchasing power through asset ownership essential.
These statistics establish a low baseline: average Americans save 5%, carry $9,000 in credit card debt, and retire with under $100,000 in retirement savings while depending on Social Security. The goal is not competition with others but securing personal financial stability first, described as putting on one's own oxygen mask before assisting others.
The speaker promotes Whiteboard Finance University at $10 monthly for education on preserving purchasing power through broad-based index fund investing, noting that trading represents only a small fraction of personal net worth.
Keep Marko - WhiteBoard Finance in your library
Save the videos and channels worth coming back to, and find them again in one place.