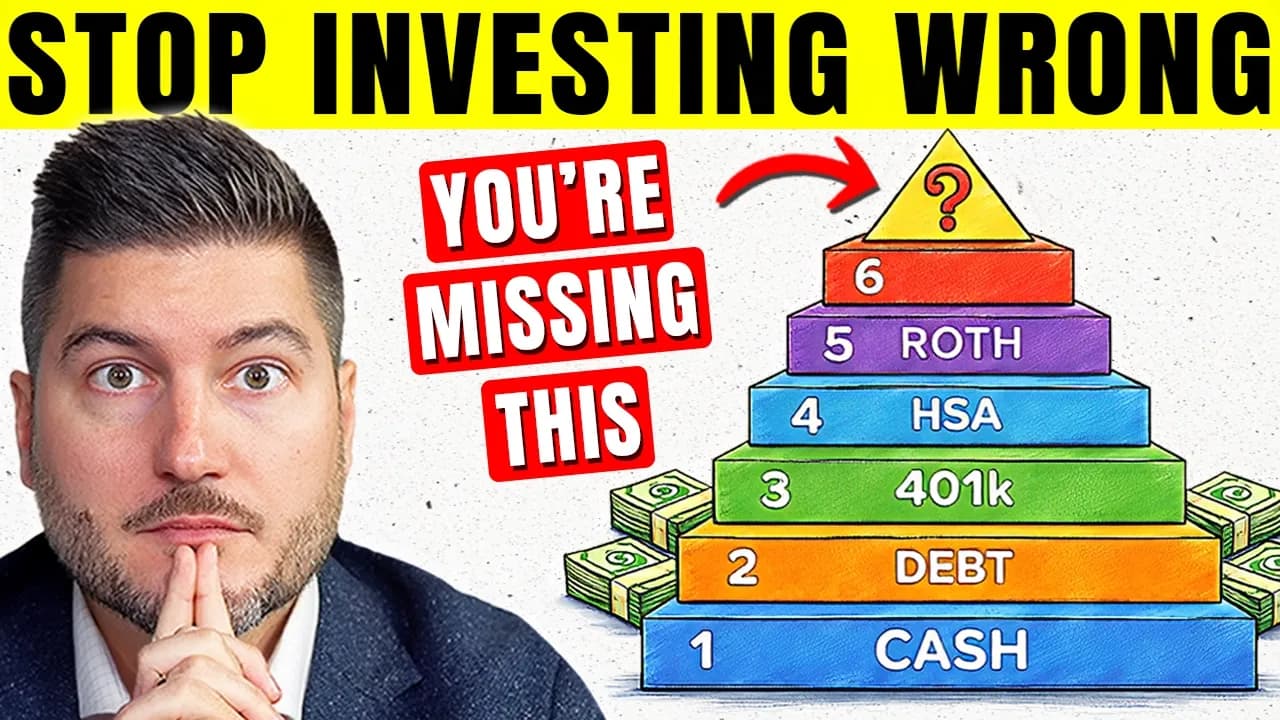
7 Ways To Avoid Taxes Legally (Do This NOW!)
In a Nutshell
Tax planning should focus on lifetime tax minimization, not just this year's bill. The highest-impact strategies include maximizing contributions to 401(k)s, IRAs, and HSAs, strategically timing income and Roth conversions during low-income years, and bunching charitable donations to overcome deduction floors. Tax-loss harvesting and proper asset location between accounts also reduce future tax drag.
These notes were generated by AI and may contain inaccuracies.
A $1.2 million retirement account can eventually force you to take almost $100,000 of taxable income in a single year, whether you need the money or not. Most people only think about how to pay less this year when sometimes the better move is intentionally paying some tax today so you can potentially pay less later.
At the time of this recording, you can contribute $24,500 into most 401k plans. If you're 50 or older, the standard catchup is another $8,000. There's now an even larger catchup for people who are 60 through 63, which is $11,250. For a 55-year-old married person making $150,000 a year who previously put $10,000 into their traditional 401k, increasing to the full $32,500 contribution (using the 50-plus catchup) puts $22,500 more into the account before federal income taxes. If those dollars otherwise would have fallen into the 22% federal bracket, that's roughly $4,950 of current federal income tax deferred.
For this tax year, you can contribute $7,500 to an IRA, plus $1,100 catch-up if you're 50 or older. The catch is that traditional IRA deductibility depends on your income and whether you or your spouse are covered by a workplace plan. Don't just assume the deduction is available.
If you're eligible for an HSA, this might be one of the best tax shelters available to a normal person. Money can go in with a federal tax benefit. The investments can grow without current federal tax, and withdrawals for qualified medical expenses can come out tax-free. For 2026, the contribution limit is $4,400 for self-only coverage and $8,750 with eligible family coverage.
If you have $4,000 of qualified medical expenses but can afford the bill from normal cash flow, that $4,000 invested inside the HSA at a hypothetical 7% annual return for 20 years becomes $15,479. If you do this repeatedly, this becomes another retirement asset. If you save your receipts and otherwise follow the reimbursement rules, there can be additional planning flexibility later.
If you pay the $4,000 medical bill with the HSA, you have zero left over. If you pay with cash instead, the $4,000 stays in the HSA and after 20 years at 7% becomes approximately $15,500.
For married couples filing jointly, the 24% federal bracket begins once taxable income exceeds $211,400 in 2026. Crossing that line does not make all of your income taxed at 24% - only the dollars that land inside that tax bracket get taxed at that marginal rate. Large income events like selling company stock, receiving severance, selling a rental property, or self-employment income timing can matter.
Moving discretionary income or a planned investment sale from December into January can mean that income lands in a completely different tax year. Taxes happen one calendar year at a time.
Once your modified adjusted gross income gets high enough, the net investment income tax applies - an additional 3.8% that can apply to certain investment income with thresholds of $200,000 for single filers and $250,000 for married couples filing jointly.
Mike (62) and Susan (60) have accumulated $1.2 million inside traditional IRAs and 401ks, $400,000 in a brokerage, and $200,000 in Roth accounts. Mike retires this year, his salary disappears, and they haven't started Social Security yet. Because Mike was born after 1960, his required minimum distributions don't begin until age 75. Their taxable income could temporarily fall off a cliff.
Mike and Susan determine they can recognize another $50,000 of income at a tax rate they're comfortable paying. They could convert $50,000 from the traditional IRA into a Roth IRA. That $50,000 is no longer sitting inside the traditional IRA going toward a future required distribution. Future qualified Roth withdrawals generally come out federal income tax-free, and Roth IRAs don't have lifetime RMDs for the original owner.
If you're paying a huge tax rate today and expect a dramatically lower tax rate later, converting might be a terrible deal. The question isn't always "How do I keep my taxable income as low as possible this year?" Sometimes the better question is "How much income should I intentionally recognize this year while my tax rate is lower?"
If the $1.2 million in traditional retirement accounts compounds at 6% per year, by the time Mike reaches age 75, the account could be around $2.4 million (specifically $2,414,636). Under the current IRS uniform lifetime table, the divisor at age 75 is 24.6. Dividing $2.41 million by 24.6 gives an RMD of roughly $98,000 for that first year.
Once you're eligible under the QCD rules, money can potentially go directly from your IRA to a qualifying charity and that distribution can count towards your RMD without the qualified amount being included in your taxable income.
For 2026, if you itemize, charitable contributions are generally deductible only to the extent they exceed 0.5% of your adjusted gross income. At $200,000 of AGI, that's a $1,000 floor. A $10,000 donation potentially gives you $9,000 of itemized charitable deduction.
Starting in 2026, married couples who don't itemize may be able to deduct up to $2,000 of qualifying cash charitable contributions.
Instead of donating $10,000 every year, put $30,000 into year 1. After the $1,000 charitable floor, you have $29,000 of potentially deductible charity plus $20,000 of other itemized deductions for $49,000 in year 1. Take the $32,200 standard deduction in years two and three. Over three years, this gives $113,400 in total deductions compared to $102,600 without bunching - a difference of $10,800, which at a hypothetical 24% marginal federal tax rate equals approximately $2,592 in potential tax savings.
A donor advised fund can potentially make bunching easier because you can make a larger contribution in the bunching year and then recommend grants to charities over time.
If you own two investments where one has a $40,000 realized gain and the other is down $40,000, selling both creates a net capital gain of zero. If you sold only the winner and the gain fell into the 15% long-term capital gains tax rate, that would be $6,000 of federal capital gains tax.
If you end the year with more capital losses than capital gains, federal rules generally allow up to $3,000 of net capital loss to offset ordinary income with unused losses potentially carried forward.
Don't sell something for a tax loss and then buy the same or substantially identical security right back. The wash sale window generally looks 30 days before and 30 days after the sale.
Tax inefficient bond investments sit better inside tax-advantaged retirement accounts while broad-based ETFs that generate relatively little taxable activity like VTI sit in taxable brokerage accounts.
Most normal people treat taxes like the weather - April shows up, they file taxes, complain for 10 minutes, and don't think about it again until next year. Once you start building real assets, taxes become another lever you can actually plan around. Start with the big obvious things: use tax-advantaged accounts, understand what bracket you're actually in, and pay attention to income timing and charitable giving strategies.
Keep Marko - WhiteBoard Finance in your library
Save the videos and channels worth coming back to, and find them again in one place.