Money Expert: Why Renting Makes You Richer Than Buying
In a Nutshell
Renting often beats buying a home financially due to unrecoverable costs like 1% property taxes, 1-2% maintenance, emergency repairs, and 3% opportunity cost on equity (5% rule: rent ≤ (home price × 0.05)/12 monthly), enabling stock investments with ~7% long-term returns and greater mobility. Top mistakes include not maximizing earnings via rare skill stacks, poor goal-setting (use PERMA framework: Positive emotion, Engagement, Relationships, Meaning, Accomplishment), avoiding index funds for 100% global equities (1/3 domestic, 2/3 international), skipping tax optimization/insurance/prenups, and chasing bad products like covered calls or thematic ETFs. Focus on controllable factors: human capital, saving habits, psychology (ignore portfolios), and efficient markets—women outperform men due to less overtrading.
These notes were generated by AI and may contain inaccuracies.
Renting versus owning a home is the biggest financial decision most people make in their life. Discussion covers unrecoverable costs of owning a home, including property taxes, maintenance costs (most underestimated), and emergency costs (stack of examples provided). Introduces a 5% rule to determine if renting is a better financial decision.
Top 10 financial mistakes people make, such as tax planning opportunities with simple actions to minimize taxes.
Ben Felix's firm manages money for more than 3,000 people, from those with huge amounts to not so much. Thesis: money advice based on academic research. Brains and psychology get in the way of good long-term financial decisions.
Answers big money questions: what to invest in (people don't need much background; those who know a little are better long-term investors; evidence shows this outperforms most strategies); mentality/mindset of long-term money makers; psychology for determining financial goals (framework developed to elicit higher quality goals).
Advice for young people: pressure to save, but research suggests it's suboptimal for young people to save. In AI world of rapid change, what to do with money now.
Report shows some viewers unsubscribed randomly. Request to check and hit subscribe button if regular viewer. Approaching significant subscriber landmark. In exchange, commit to bringing desired guests and conversations weekly/monthly.
Approach: draw from academic literature by smart people to apply to good financial decisions for typical person.
Key questions: renting vs. owning (biggest for everyone); asset allocation (how much to invest long-term money you can risk); why not do other attractive investment strategies.
Audience: applicable to everyone, regardless of net worth ($10,000 or $10 million); same principles for saving for future.
Investing solved: use index funds. Hard part: psychology gets in way; brains designed for survival, not long-term abstract concepts like investing today for retirement.
Best mental approach: do not look at investments. Academic paper shows more frequent checking leads to less risk-taking and lower returns. Daily checks show volatility (down 5%, up 6%), seems risky, leads to less stock investment. Long-term buy-and-hold stocks safer than perceived.
Props: PERMA model from positive psychology (for investing well and determining strategy); top 10 financial mistakes; three steps for investing first $10,000; unrecoverable costs of homeownership (stack provided).
Ben Felix background: degree in mechanical engineering at Northeastern University. Approaches finance like engineering, unlike car-dealership style product selling in financial services. Read academic literature for high-quality advice.
No need for background knowledge/economy understanding. People get stuck thinking they need it (e.g., researching sectors for portfolios). Sensible investing: low-cost index funds to capture market returns (historically and expected long-term). Knowing just enough for conviction outperforms knowing enough to hurt yourself.
Different by age. Young people pressured to save (retirement/home) by parents/society, seen as irresponsible not to. Research: suboptimal for young to save; save more with higher income, less with lower. Young may not need to save much. Risk: bad habits of spending all, no later shift to saving.
At 50: if never saved, need to save a lot; if saved, focus on other topics.
- Not earning enough money: Controversial; people think no option, but invest in human capital (formal education, skills, entrepreneurship) to increase value/earnings. Stuck mindset problematic.
- Career buckets: knowledge and skills first (knowledge applied becomes skill; hard to lose). Then resources, network, reputation (can fluctuate).
- Young: optimize rare, complementary, market-valued knowledge/skills stack. Life lands around their value/rarity/complementarity to market demands.
Data: mechanical historical relationship between education/trade and lifetime earnings; higher for engineering, finance, business, sciences.
Example: engineering + finance + YouTube content creation = rare stack (one of 100 on earth); added content skill boosted earnings. Took 3 years practice to smile on camera.
Example: biotech writer with base knowledge paid $250k vs. $50k elsewhere; 5x earnings from right market. Marketing for Uber/fizzy drinks/Dresslar vs. biotech IPO companies ($8M six-month contract). Skills + right market/industry wildly changes earning potential. No full control, but increases odds.
- Not saving enough: Young maybe less, but must start eventually. Wealth compounds; late start misses it, hard to catch up. Wake at 50-60 realizing too late. Parallels health: poor habits compound to irreversible issues like heart disease at 55.
Analogy (The Slight Edge, Jeff Olsen): brushing teeth - skip day/week/month fine, but 5 years later dental issues irreversible. Same for finance.
- Not setting financial goals: Leads to default actions (earn more, buy house). No reflection on good life components. Years/dollars wasted on irrelevant things; compounding makes irreversible.
-
List your goals (paper/app): e.g., be a dad, buy Ferrari, holiday to Cancun, retire at 50.
-
Double the list: Forces deeper thinking; research shows elicits more meaningful goals.
-
Apply PERMA model (categorical prompt; evidence-backed for meaningful goals):
- Positive emotion: enjoying daily, feeling good.
- Engagement: flow state (challenging at skill level; e.g., podcasts, research, scripting).
- Relationships: strong ties (friends, family, colleagues).
- Meaning: part of bigger thing (religion, community, business).
- Accomplishment: achieving hard goals.
Fit goals to PERMA categories for higher quality. Ferrari example: may not fit (unless track engagement, Ferrari buddies relationships); hedonic treadmill for positive emotion; maybe accomplishment if childhood dream.
Few people thoughtfully define good life; busy with daily lives, drift short-term. Helps avoid future regrets; trade-offs (e.g., overindex accomplishment sacrifices relationships).
- Overspending on wrong things: Related to goals.
When spending on things not contributing to a good life, like $12 iced coffee rushed to work without enjoyment, it prevents saving for desired life goals. Not taking investment risks is a major mistake. The stock market delivers incredible long-term returns and should continue. Many avoid stocks entirely or invest too conservatively, incurring large implicit costs by missing economic gains.
Historical and expected stock returns average 7% long-term vs. 2% in cash, a 5% opportunity cost. Compounded, $10,000 at 7% over 40 years grows to $150,000. Spending $10,000 today (e.g., small car) equates to spending $150,000 in future value. However, consider enjoyment or utility, like a car enabling a better job.
Today if I spend $10,000 I'm actually spending $150,000.
$10 coffee with toppings, invested at 7% over 40 years, becomes $150—enjoy it if spending.
PERMA (positive emotion, engagement, relationships, meaning, accomplishment) optimizes spending today alongside future value. Money is worth a lot now if spent right.
Not taking enough risk is bad; taking wrong risks worse. Index funds deliver ~7% returns, but many pick individual stocks, trade options, or crypto with negative expected returns or high trading costs eroding growth.
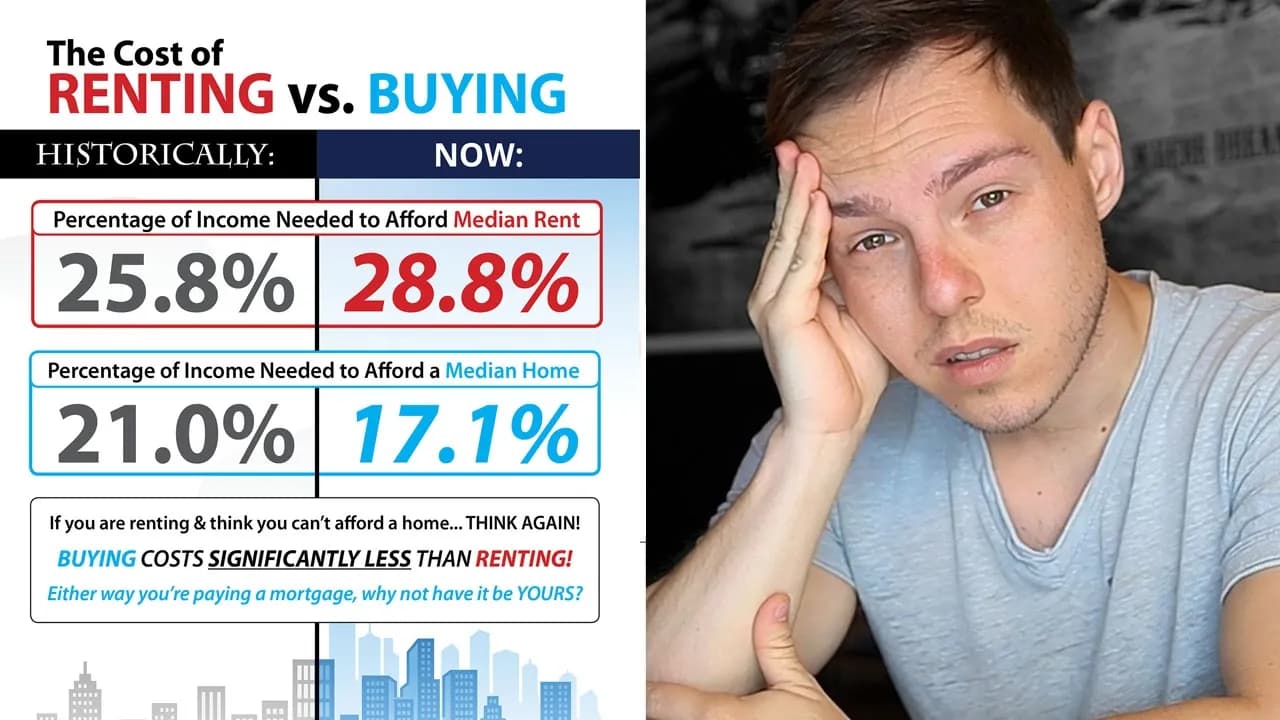
A primary residence funds housing consumption, like imputed rent dividend, but compare side-by-side:
- Owning: 20% down payment (Canada), mortgage, maintenance, property taxes.
- Renting: Invest 20% down payment and monthly cash flow difference in stocks.
Unrecoverable costs of owning:
- Mortgage interest: Paid to bank, gone.
- Opportunity cost of equity: Money in home vs. stocks (homes appreciate ~inflation; stocks far outpace).
- Property taxes: 0.5-1%+ of value.
- Maintenance costs: 1-2%+ of value/year (academic literature; speaker's experience >2% after 6 years owning). Underestimated—includes gardening, pool pumps, cracks, heating, constant breaks.
- Time wasted coordinating contractors (phone calls, waiting; outsourcing expensive).
- Emergency costs: Roof, foundation—require liquid cash (more opportunity cost).
- Renovation spending: Fixes improve beyond baseline (not done when renting).
Financial equivalence exists. 5% rule: ~1% property taxes + 1% maintenance (low estimate) + 3% opportunity cost = 5%. Monthly equivalent rent = (home price × 0.05) / 12.
Example: $300,000 house → $15,000/year → $1,250/month. Rent at $1,250 or less? Renting better financially.
PWL calculator refines with specifics (asset allocation, taxes). Taxable investors: lower opportunity cost (after-tax stock returns drop vs. tax-free primary residence gains in Canada/US).
Tough for young: high prices require big down payment; limits mobility (e.g., Toronto condos plummeted; stuck if job elsewhere). High transaction costs. Needs change (speaker rented 4 places with growing family—kids, bigger spaces—easy moves vs. owning costs).
Psychological trap: Homeowners hesitate job opportunities elsewhere (e.g., New York, LA, London).
If certain to stay (e.g., 4 kids in same school), buy to avoid pricing out (happened in Canada; reversed now). Risk-averse, long-term stayers, high-tax investors suit owning.
Holiday homes bad: limits vacation spots, mental overhead (speaker avoids second property).
Studies (Statistics Canada): Control for property/neighborhood—no happiness difference. Uncontrolled: Owners in nicer areas. Forced cheap rentals in bad areas reduce happiness, not renting itself.
Past gains (e.g., $100k to $600k, $70k to $1M) ignore risks, leverage in hot markets.
Comment responses:
- UK: Rents > mortgages ignores full owning costs (taxes, maintenance, opportunity, renovations). Rent from professionals, long leases (speaker did 6 years with family/kids successfully). Stability for family possible.
- Psychological impact: Valid if truly profound after reflection—not for everyone.
- Personal story ($1,800/mo total own vs. $4,000 rent; 3x value): Leverage wins in up markets, but Canada now biggest inflation-adjusted drawdown since 1975 (peaks 2021/2022 hurt buyers).
Past drivers (low rates, immigration > supply) normalizing; don't expect stock-like real estate returns forever.
Best for wealth + mobility: Index funds over homeownership (financially equivalent, but mobility key).
If mobility matters, renting provides flexibility. Unique investment opportunities can create high opportunity costs. Example: Speaker had a chance to buy equity in his company but had just bought a house; a well pump broke, forcing him to reduce the equity purchase. Opportunity costs in stocks average 7%, but specific situations can be higher.
Optimize tax-advantaged accounts: In Canada, RRSP and TFSA; in US, Roth IRA, traditional IRA, and 401(k). Higher-income people have country-specific options to pay less tax. For lower-income people, government accounts like ISA in UK are key, though often not used optimally.
Rich people hire professionals and use strategies like starting side businesses for real estate licenses to reduce taxes or taking loans against stocks (e.g., $1M Facebook stock for $500K tax-free loan, borrow more as it grows to $2M). Risks include margin calls if value drops; banks may sell stocks post-decline. Rules apply to everyone, but borrowing against risky assets like S&P 500 is high-risk.
For average people, consult a CPA (accountant) or good financial planner/tax professional to identify opportunities. Most strategies are simple to optimize once and done.
Many need financial advisors, but industry is sales-driven; risk of being sold unneeded products at banks or firms. Solution: Seek trusted referrals from friends/family, though people often trust poor advisors. Many don't need advice due to fees; finding the right person is key.
Plan asset distribution to desired people/entities upon death. Avoid higher taxes and unintended beneficiaries. Country-specific; improper setup leads to excess tax.
Everyone with dependents should write a will. Estate lawyer joke: Everyone has a will—the government's default, which you may not agree with. Like prenups, it prevents mess for others, especially with kids.
Academic research identifies tightwads (dislike spending) and spendthrifts (like spending). Tightwads and spendthrifts more likely to marry each other than same types (opposites attract for thrill, but leads to less marital satisfaction and money conflicts).
Financial impact: Mismatched profiles hinder saving goals if one spends heavily. Possible to make it work with coordination/communication.
Discussed often with clients entering relationships/marriages: marriage contracts/prenups, estate planning. Everyone should consider prenup (government defaults asset division on breakup). Prenups seen as unromantic/assume failure, but if both comfortable, no rift—red flag if it causes one. Not about keeping assets separate; agree on split if 50% chance it fails. Creative contracts possible (e.g., formulas based on kids). Bad divorces without them are financially devastating.
Anecdote: Friend's drawn-out divorce (6-7 years) destroyed relationship due to lawyers incentivized to maximize fees; prenup could have made it quick, saved relationship (two kids involved).
Tightwad-Spendthrift Quiz (Carnegie Mellon/University of Michigan)
Measures pain of paying (emotional distress on spending). DIY version:
-
High-quality coat on sale: $100 (usually $300), need it, have money.
- A: No, $100 still a lot; wait for better deal.
- B: Yes, great value; need it.
- C: Yes, might buy scarf too (saved so much).
-
Restaurant bill split evenly, you ordered cheapest.
- A: Physically pained; mention paying less.
- B: Bit annoyed, pay to keep peace.
- C: Fine, evens out.
-
Describes you:
- A: Trouble spending even on needs.
- B: Balance spending/saving well.
- C: Spend more than intended, regret later.
-
Buying expensive item emotion:
- A: Anxiety/regret.
- B: Satisfaction in utility.
- C: Excitement/rush.
Scoring:
- Mostly A's: Tightwad.
- Mostly B's: Unconflicted (healthy money relationship: save when needed, enjoy without guilt).
- Mostly C's: Spendthrift (little spending pain, enjoy moment, struggle with long-term saving/buyer's remorse).
Hosts score: One unconflicted (mostly B's), other spendthrift (mostly C's). Suggest playing quiz on date (e.g., via podcast). Opposites attract but conflict; same types better (two spendthrifts need caution). Middle partner useful.
Critical if not financially independent and household relies on your income. Need sufficient life insurance (replaces future earning power/human capital if you die) and disability insurance (replaces income if unable to work). Not enough people think about it. Term life insurance cheap; disability less so.
Paper simulates 1M lifetimes using data from 39 countries (back to 1890). Tests how stock/bond mix should change over life.
Conventional wisdom: Start risky (stocks), shift to safe bonds with age (e.g., target date funds auto-shift to more bonds).
Findings: 100% equities optimal (1/3 domestic stocks, 2/3 international). Best for retirement consumption utility (spending satisfaction), bequest utility (money left at death), probability of not running out of money.
Domestic = your country (e.g., US investor: US stocks); international = rest of world. Bootstrap simulation weaves 10-year return blocks (e.g., US domestic + others international in USD; repeats for other countries/currencies).
For US: 30% domestic fine; curve flat 10-50% domestic (market-cap ~60-65% OK). Non-US (e.g., Canada) advised against heavy home country bias.
Reason: International diversifies vs. domestic issues like high inflation (hurts consumption/stock returns). Controversial/extreme vs. conventional wisdom; co-author on podcast twice. Shows stocks safer long-term than thought; bonds riskier (decimated in high inflation).
Bond: Debt instrument; lend to government, get interest payments + principal back.
What is the most important thing we haven't talked about that your audience comes to you to understand? A lot of the things I talk about are financial products that you should not invest in. A big one I spent quite a bit of time on last year, doing three videos, was on covered calls.
Covered calls are where you own a stock and then sell a call option, which is the option to buy the stock. You're selling that option to somebody else, which gives you an option premium. You get some income from having sold the call option. But if the stock you own appreciates sufficiently, you are required to sell it to the person who bought the call option from you at a preset price. For example, the stock is $40, you sold a call at $50, and the stock goes to $60; you have to sell it at $50. You're giving up a big chunk of your upside.
This plays on one of the big biases investors have: a preference for income. It's the mental accounting bias where investors separate capital and income. There's a huge proliferation of covered call products where they do that strategy inside an ETF. They charge usually a higher fee, marketed heavily to investors on the premise that you're going to get capital appreciation and income. But you're giving up so much upside that most investors don't realize; the implied cost of these products is enormous.
On fees, a graph shows the impact over time. When investing in ETFs and index funds, people often don't think about fees like 0.5% or 1%, thinking they're small. But fees compound, and any rate of return that compounds over long periods can be very impactful in dollar terms.
Some people keep money in cash because they're not educated on inflation. For example, keeping $10,000 under the bed. Inflation is everywhere, throughout history, and probably not going away. Central banks in most developed countries target a low but stable rate of inflation for reasons. If money sits under the mattress, its purchasing power decreases over time, damaging wealth.
You can keep pace with inflation using short-term government debt instruments that pay a little interest, but periods of high inflation can cause even that to decline in real value. For long-term investors, the best way to fight inflation is investing in low-cost index funds to avoid fees and participate in the stock market, which throughout history has far outpaced inflation.
A graph shows the impact of inflation on cash under the mattress over 20 years: start with $10,000 in purchasing power, at 3% inflation, 20 years later you have $5,336 (source: St. James Place). You're effectively losing half your money. A lot of people holding cash don't realize that over 20 years at 3% inflation, they're halving their money. It ties back to one of the biggest mistakes in personal finance: not investing, not taking the right kinds of risk. Hoarding cash is taking a type of risk with no expected return; in real terms, a negative expected return.
Everyone should think about retirement planning. It ties into designing the life you want, but at some point, most can't work into their 80s. It's sensible to plan for that. Many don't want to work forever; they might choose lower-paying work, but being forced to work forever isn't attractive. Building financial independence by saving and planning for retirement is important for everyone.
The social contract of retirement is changing. Pensions from companies and governments used to be more common; now the onus is back on individuals. Retirement has changed, but not necessarily a crisis. People have more personal responsibility now but better tools. 30 years ago, low-cost index funds were just starting to proliferate; prior, you paid 2% or more for mutual funds. Tools are better today, but more responsibility on personal finances.
Other problematic investments: thematic ETFs, like AI ETF, space, energy, or any specific theme.
What happens: something becomes hot (AI, cannabis, electric vehicles, sustainable/clean energy). Asset prices go up due to interest. An index provider creates an index for that theme, then an ETF launches when prices are high. Then asset prices come down, and returns on thematic funds tend to be very poor.
Example: sustainable energy ETF created when it was hot. Instead, invest in broader baskets like FTSE 100 or S&P 500. Technology has performed incredibly well but is one sector. If you invested in tech for the last 20 years, well done, but concentrating in tech today is less obvious. For AI, much is private; public companies own chunks of private AI firms. Retail investors struggle to access private companies like SpaceX. Products claiming access charge high fees; not obvious they bought underlying securities at good prices. Financial firms prey on investor desires and biases, creating products to fulfill them even if not good.
For someone 50 years old with $10,000 in cash, to grow over 10-20 years: personally invest in stocks with a globally diversified stock portfolio with Canadian home country bias (like the controversial paper found; done prior to that paper). Makes sense for most, including retirees.
Risk tolerance matters: if they panic and sell when market goes down, won't get good long-term outcome. 100% stocks is a portfolio personally comfortable with, not expected to change through life cycle. Personal allocation: home, stock market investments, significant equity in company worked for. No crypto.
Bought $1,000 each of Bitcoin and Ethereum while researching to participate while learning.
Cryptocurrencies: solved interesting problem of digital cash without trusted third party (cypherpunk community, libertarians, privacy-focused). Satoshi Nakamoto solved it, using pieces like Adam Back's ideas to stop email spam. Fascinating technology and story. Became ideological vehicle (world/government role in money) and speculative asset (buy because think it will go up). Personally wouldn't invest; PWL doesn't allocate to it for clients.
Friend called amid wars (Strait of Hormuz closed, Russia-Ukraine): article from October 10, 1847 magazine: "It is a gloomy moment in history. Not in the lifetime of any man who reads this paper has there ever been so much grave and deep apprehension. Never has the future seemed so dark and incalculable. In France, the political cauldron seethes and bubbles with uncertainty. England and the English Empire is being sorely tried and exhausted in a social and economic struggle. The United States is behind industrial and commercial chaos drifting. We know not where. Russia hangs like a storm cloud on the horizon of Europe, dark and silent. It is a solemn moment and no man can feel indifference. Of our own troubles, no man can see the end."
Sounds like today. World has been through crazy times, wars, turmoil, upheaval; we've come out okay. Stock returns positive despite craziness. Charts overlay news headlines of madness on stock charts going up. Volatility happens (e.g., stocks negative briefly at war start, then recovered), but long-run stock returns expected positive. Globally diversified stock exposure doesn't need changes when world gets crazy.
Friend considering remortgaging paid-down house: buy another house or invest in stock market? Probably stock market, not real estate.
Leverage: borrowing to invest in positive expected return assets like stocks good on paper, improves long-term expected outcomes. But stressful, can lose all money. Personal question like stock vs. bond allocation; depends on goals/situation. Data says borrowing to invest not terrible.
AI changing equation? Anthropic report: entry-level people hard time; 13% of entry-level jobs disrupted by AI/AI agents.
Not a labor economist, but history shows technological revolutions caused upheaval: ATMs thought to wipe out bank tellers, but cost of bank branches decreased, more branches opened, more bank teller jobs.
Jevons paradox: coal became cheaper as coal engines more efficient; coal industry thought doomed, but trains used for travel too, coal boomed.
Applies to AI: cost decreases, proliferates, expands market. Companies save money, invest elsewhere, create jobs.
Concerns: speed of AI adoption, robotics (self-driving cars, one of biggest employers is driving; warehousing/supply chains; factories with head cameras for robots to replace hand labor).
Speed different (like internet, deploy instantly). Where do displaced people go? History: same worry, unemployment, hard times, but worked out. As individual: develop complementary skills making you unique (e.g., content creation). As investor: technological revolutions changed world/markets/culture repeatedly; cycle repeats with unemployment, unrest, inequality.
Book: Technological Revolutions and Financial by economist Carlota Perez.
Capital. She documents this exact cycle throughout history. Part of it is asset prices getting really high and then coming back down. Worried about a catastrophic market collapse? It's always a concern and part of the risk of investing in stocks. We never know when it's going to happen or what the trigger will be. Can't do anything about it. Need an asset allocation that you can stick with even if that outcome materializes.
In that book, does it suggest the writing is on the wall for the current economy with heavy investing in AI and data centers? A couple years ago, everyone invested in crypto, Web3, NFTs, and money got sucked out of almost every industry into AI. DeFi was going to kill banking and finance, but developers moved to AI. Startup friends getting nervous, raising money now because they think in the next couple years, maybe 24 months, big market contraction. Investors in startups with $100 million valuations realize they're losing money, domino falls, catalyst triggers contraction, stock markets go down, hard to raise money. Clients lower advertising budgets. Prepare for that scenario. This is part of the cycle. Cost of capital for bubble companies (companies in the focus of technological revolution like AI) gets low, asset prices high, but not sustainable, tend to come down. Does that mean total market collapse or catastrophe for diversified investors? No.
If the writing were on the wall, prices would reflect that today.
If market prices going to drop in future, they drop today. Happens when no one expects it. Writing is never on the wall. Some new information changes, causes prices to come down.
Brother (smart, 15 years investing): When investing, assume price (e.g., Facebook stock at $10) is total accumulation of everything everybody knows about company, priced in today. Even if you think it'll go up, that's priced in. Better know something no one else knows.
Describes efficient market: theoretical concept where prices always fully reflect all available information, including thoughts about future price. If you trade on those thoughts, it's priced in. What to invest in if futures priced in? Discounted future cash flows. Companies produce cash flows, earn profits. Buy expected future profits at a discount (discount rate). Value of stock is discounted future cash flows. Riskier stocks have higher discount rates. Hold asset, receive discount rate as rate of return.
Example: People invest in Tesla because they have one, think great car, will do well. Fault? That information already in price. Everybody knows it's good company making good cars selling well, why it costs whatever today.
Data on professional money managers trying to beat market: most don't. Ones that do beat over time don't tend to beat in future (before or after fees, similar; worse after fees). Point in money manager trying to beat by picking stocks/timing? No. Buy index funds. Buy the market, accept market's return, which has been very good. Don't check it, don't open app, lose password.
Anecdote: Fiancée good at investing because forgets password. Four years later, check: "Babe, you're rich." She forgets again.
Focus on things you can control: appropriate financial plan, right goals, asset allocation that makes sense even if markets decline, emergency savings, tax planning. Can't control markets or performance relative to market. Trying to outperform makes you worse off.
Women more risk-averse, less overconfident, better results. Women probably better investors.
Data:
- Fidelity: across 5.2 million accounts, women beat men.
- War business school: women outperformed men by 1.8% per year over three years.
- UC Berkeley: men traded 45% more often than women, annual returns 1.4% lower.
- Revolut (UK bank): women's investments outperformed men's by 4%.
Related to overtrading. Men overconfident, trade more, pick stocks like Tesla because like car. Men biggest gambling addicts.
Experiment whose outcome contradicts current beliefs (markets efficient, hard to outperform): try to beat it (being run all the time).
Warren Buffett bet Ted Seides (on podcast): S&P 500 index fund vs. hedge fund picks over 10 years. Buffett won, donated proceeds. Exposed index fund idea.
YouTube: Ben Felix (link below).
- Rational Reminder podcast (posts more frequently, longer form): rationalreminder.ca/podcast.
- Tools: rent vs. buy calculation, goal setting app (not up yet), other tools on PWL Capital website: pwlcapital.com.
Finance important, huge percentage avoid due to anxiety, not taught in school. Destroyed credit score before learning. Podcast and experts like Ben (uses academic research) demystify. Knowledge is power, empowers control in uncertain world.
Keep The Diary Of A CEO in your library
Save the videos and channels worth coming back to, and find them again in one place.