The 4 Proven Ways To Build Wealth In 2026
In a Nutshell
The four proven wealth paths are bootstrapping your own business, raising investor capital for your business, investing in others' businesses, or managing funds that invest other people's money in other businesses. Bootstrapping gives full control but slower growth; raising capital accelerates scale but dilutes equity and adds investor pressure; investing offers diversification with lower effort but capped upside; fund management delivers maximum leverage through fees and carried interest but carries heavy fiduciary responsibility. Most Forbes billionaires built wealth via bootstrapping or raising capital, and the optimal path depends on your risk tolerance, capital access, and whether you want to operate or allocate.
These notes were generated by AI and may contain inaccuracies.
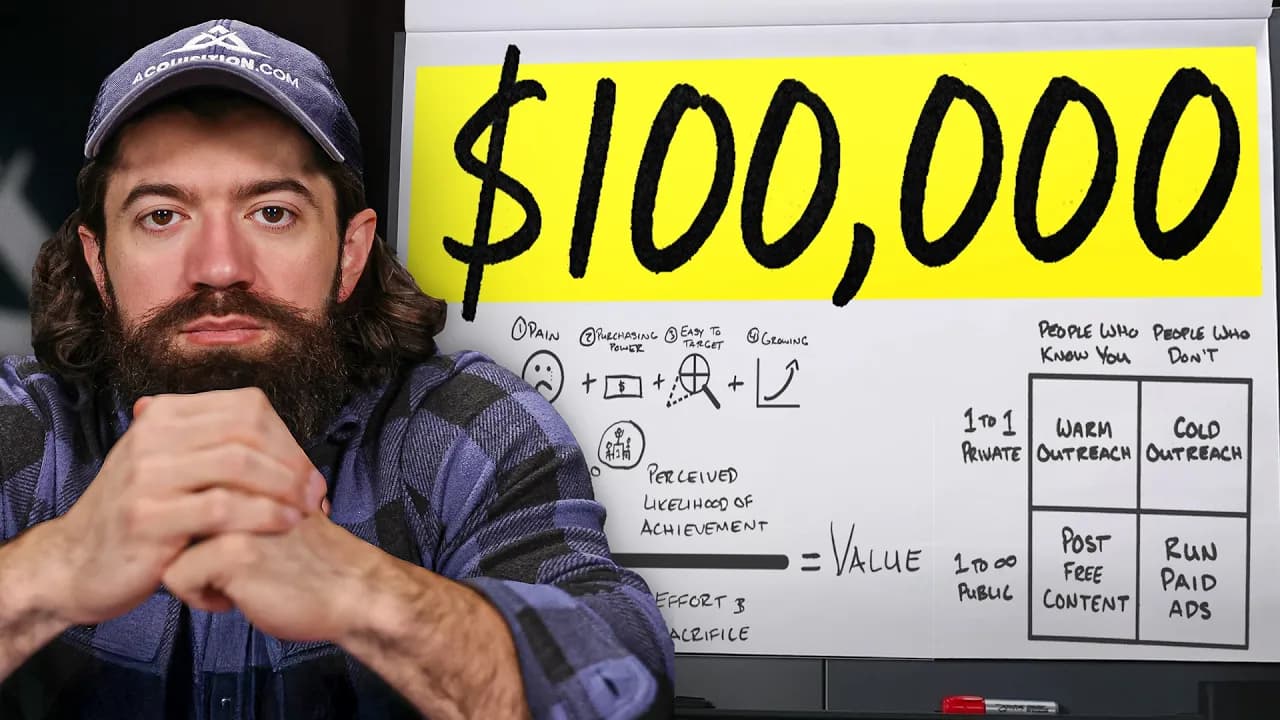
Poor people stay poor because they want a fast way to get rich. The richest people pick one of four paths, play it for a decade, and end up with more money than everyone chasing shortcuts. No president or economy will make you rich—you have to do that for yourself. The four paths come from combining two variables: your money versus other people's money, and your business versus other people's businesses.
The four combinations are:
- Your money and your business = bootstrapped business
- Other people's money and your business = raising capital
- Your money and other people's businesses = investing
- Other people's money and other people's businesses = fund management
The speaker examined the top 11 richest people on the Forbes list and their paths:
- Elon Musk: raised capital
- Larry Ellison: raised capital
- Mark Zuckerberg: raised capital
- Jeff Bezos: raised capital
- Larry Page: raised capital
- Sergey Brin: raised capital
- Steve Ballmer: bootstrapped (Microsoft)
- Jensen Huang: raised capital
- Warren Buffett: investing
- Michael Dell: bootstrapped
- The Waltons (Walmart): bootstrapped
Fund management does not appear in the top 11, but appears when going six names deeper. The speaker has personally done all four paths.
Bootstrapping means funding the business from your own savings and cash flow with no outside investors, growing through reinvesting profits. You start with a website, cell phone, and skills, trade them, generate excess money, and reinvest to continue building.
Typical low-cost examples include service businesses such as agencies, home service businesses, B2B services, professional services, education businesses, drop-shipping e-commerce brands, and local businesses. Software businesses have become more feasible to bootstrap due to dropping entry costs.
Personal examples: first brick-and-mortar business was a gym (bootstrapped), used profits to start Prestige Labs (supplements, bootstrapped), started Acquisition.com (software, bootstrapped). Acquisition.com now invests some capital into other businesses while starting companies de novo from the holdco, which is semi-bootstrapped and reinvests its own capital.
If this is your first business, start with bootstrapping to pay off ignorance debt before risking friends' and family's money. Bootstrapping is typically the slowest of the four paths because it takes money to grow, and you must generate that money internally—similar to building a car factory inside the car.
Advantages: you keep full control and equity, decide pace and strategy, and can exit on your own timeline or never exit. The goal is to design a compounding vehicle that is either recurring or reoccurring.
Trade-offs: you incur more non-financial debt than other paths, including management/leadership debt, technical debt, and data debt. You struggle to attract top talent who need high compensation. You can stay alive longer with a lower cost basis, but capital constraints limit the size of opportunities you can pursue from day one. Capital-intensive opportunities like AI robotics businesses are extremely difficult without outside capital.
Raising capital means starting and running the company while raising money from investors who buy equity slices to fund fast growth. Typical examples include tech platforms, social networks, marketplaces, manufacturing, and pharmaceuticals that require years to reach profitability, have huge upfront costs followed by increasing margins, or exhibit winner-take-all dynamics with network effects.
Examples: Amazon lost money for over a decade before turning a profit; Facebook lost money for a long time while mapping networks. The speaker raised capital for Acquisition.com (formerly referred to as "school") to grow the company and offer tools at $9 per month.
This path suits those with a very big dream where the business cannot become profitable without outside money and will lose money for one to three years. Advantages: you start bigger, hire top talent, outspend competitors, acquire customers at a loss, build infrastructure faster, and incur less personal debt. You can pursue rarer, high-risk high-return opportunities that price many competitors out of the market.
Using the car analogy: you build the car factory first, lose money upfront, then profit on every car produced once the factory is complete.
You now have two customers—the end customer and investors (venture capitalists)—who must both be served and whose interests can conflict. You dilute your own equity. Liquidation preferences and ratchets can reduce founder payouts even in large exits. Multiple rounds often bring board seats, risking loss of control; Steve Jobs was voted out of his own company. Terms matter enormously—a trillion dollars for 1% equity is excellent, while $10 for 90% equity is difficult.
Venture money is grand-slam economics: investors expect many strikeouts but need a few 1,000x wins. For founders, failure means 5–10+ years of high stress with nothing to show, which is far more common than headline successes.
Investing means taking cash earned actively and buying pieces of other people's companies—public stocks, cash-flowing businesses, real estate, or venture deals. You fund them but do not run them. The speaker splits investing between HQ Ventures (venture arm focused on SMB tech) and private-equity-style investments that also add a service layer through Acquisition.com.
This path fits people who have meaningful excess cash and want upside without day-to-day operational responsibility. Advantages: diversification across many bets instead of one life-or-die company, and an easier lifestyle with no boss while technically being other people's boss—you simply write checks.
Diversification decreases upside. Most successful investors are more concentrated, making five to seven significant bets where they believe they have alpha. This is the slowest path and almost no one makes their primary wealth this way; they already have high active income and then begin investing.
Warren Buffett bought his first stock at age seven after Pearl Harbor and made the vast majority of his wealth between ages 80 and 95. Main Street real estate is the most common path for creating millionaires but not billionaires. It is an excellent way to build and store wealth but unlikely to reach the absolute top without an extremely long time horizon.
Fund management means raising a pool of capital from limited partners (LPs) and investing it into other people's businesses, sometimes using debt for additional leverage. This path offers the highest leverage.
Example with large numbers: raise a $100 million fund by putting in $5 million (5%) of your own money and raising $95 million from LPs. Use $200 million in debt to buy $300 million worth of businesses. With a 10% annual return, the portfolio doubles to $600 million in seven years. After paying back debt and LPs (including any hurdle rate of 6–8%), the remaining profit is split between LPs and the GP (general partner).
With a 20% annualized private-equity return over six years, $300 million grows to $900 million. After debt repayment (including interest) and returning LP capital plus minimum return, the GP share of the remainder can be substantial due to the leverage on the initial $5 million.
This is potentially the highest-leverage scenario of the four paths.
After the preferred return or hurdle rate is paid to limited partners, remaining profits are split between the general partner and limited partners. With a 6% preferred return on a $500 million fund, approximately $40 million would go back to LPs before any profit split occurs. A 50/50 split on remaining profits could result in a $465 million profit pool after all calculations.
A $5 million investment can generate substantial returns through fund structures. With a 10% stake in a $465 million profit pool, an investor would receive $46.5 million. A 20% stake would yield $90 million. This demonstrates how leverage through fund management creates outsized returns compared to direct capital deployment.
There is no lack of capital in the world, only a lack of good deals. If you find a good deal, capital will appear. Investors ask how much money is needed when presented with strong opportunities backed by credible risk mitigation strategies. The higher the returns and the more niche or private the deal type, the better the GP profit splits that can typically be negotiated.
The optimal approach involves building a track record, developing proprietary deal flows that come exclusively to you, and establishing a real edge in selecting and improving companies. Funds are often organized around a singular thesis. Maximum leverage is achieved with the smallest personal capital checks while maintaining huge upside potential. Fees can be added as track record and reputation grow, though first-time funds often have lower fees to align incentives with investors.
Walnut Tree Fund Example
A walnut tree fund was presented as an investment opportunity where trees take 30 years to reach full size but generate cash flow annually after year three. At the end of 30 years, the trees are harvested for valuable walnut wood. The business model involves staggered tree vintages with each year representing a new cohort. The fund structure allows investors to participate without needing direct connections to Venezuelan tree farmers or expertise in scaling walnut sales.
The GP often ends up richer than any single LP, depending on total capital deployed. GPs can charge management fees in addition to carried interest. First-time fund managers typically charge lower fees to attract investors and demonstrate aligned incentives.
Fund management carries enormous responsibility with a very long feedback loop. GPs are accountable to LPs, regulators, entrepreneurs running portfolio companies, and to some degree the customers those businesses serve. This creates multiple masters to serve simultaneously. GPs can be rich on paper while feeling like a slave due to ongoing obligations. The role shifts from building individual companies to managing risk, reputation, people, and portfolios. The fund itself becomes the primary company being built.
The speaker got rich by bootstrapping companies, took cash to invest in other people's companies where it continued compounding, invested in and co-founded School, and eventually moved into fund management. Real estate deals have been executed through ACQ Real Estate, raising capital privately from higher-level clients and portfolio companies. These represent the four paths to building significant wealth, and individuals should select the path aligned with their skills and circumstances.
Keep Alex Hormozi in your library
Save the videos and channels worth coming back to, and find them again in one place.