10 Money Lessons You Must Know in Your 20s
In a Nutshell
The core message is that wealth isn't built through credit scores, debt, or get-rich-quick schemes—it's built through consistent systems like debt-free living, long-term investing in mutual funds, and compound interest over 12-17 years. The largest study of millionaires shows 79% inherited nothing and most are ordinary professionals (engineers, teachers, accountants) who followed boring, steady processes like funding 401(k)s, paying off homes in ~10 years, and practicing delayed gratification. Success requires emotional discipline to manage your mind during setbacks, building competence before expecting confidence, and surrounding yourself with achievers who believe it's possible.
These notes were generated by AI and may contain inaccuracies.
You're not bad with money. You were just never taught how to use it. You were taught how to earn it, not how to grow it. You were taught how to spend it, but not how to invest it. You were taught to chase it, not how to make it work for you. You weren't taught about investing, only about surviving. And it's not your fault you didn't know, but it's your power to learn. Financial literacy is something we all learn far too late. It's something that some of us never learn at all.
People face challenges with credit card payments, debt, understanding how to make money or grow money, whether they need a side hustle, how many streams of income they have, knowing where they're spending money, and knowing where they're wasting money. There's often avoidance of money, not liking to look at bank statements, wanting to put it away, not checking how much has been saved because of fear.
It's not your fault. You were never taught how to do it. It's not something you should know how to do. We grow up and suddenly we're paying rent, paying taxes, figuring out what a mortgage is, and everything has interest. No one taught this in school. Even if you studied economics at school, you didn't know how real world economy worked. Even if you studied finance at university, you didn't necessarily know how to start and run a business.
Dave Ramsey grew up in a household of entrepreneurs where they taught that you can do it, that all you've got to do is leave the cave, kill something, and drag it home. They believed the free enterprise system is not broken, it's tough and hard, but you can do it. Ramsey got his real estate license at 18, and after college started buying and selling real estate. Starting from nothing, he got rich by Antioch, Tennessee standards with about $4 million worth of real estate and a little over a million dollar net worth, making a couple hundred thousand a year in 1982.
However, he had borrowed too much money. The bank got sold to another bank and they called their notes. They were doing flip this house before Chip and Joanna were born. The bank called their notes and they spent the next two and a half years losing everything they owned. They were sued and foreclosed on with a brand new baby and a marriage hanging on by a thread. They had the opportunity to start over after bankruptcy. It was brutal, gut-wrenching, life-defining, and the worst trauma at the time.
Thirty years later, Ramsey realized this was the best thing that ever happened to him because he learned a whole new way of looking at money. He realized that borrowing money was a bad plan. They've since been able to put lots of data to that idea that if you don't have any payments, you've got money and you can build some wealth. They began a debt-free life at 28 years old, and at 62, it's worked out pretty well.
There's a level of mythology that has been spread about money in our culture that was spread with an agenda. If Ramsey was a bank, he would teach everyone that they needed a credit score. The way to get a credit score is to borrow money from the bank and pay it back to raise the score so you can borrow more money. It's a great plan if you're a bank. The FICO score is a banking program to get people to borrow money, but now it's been accepted as biblical truth or norm rather than actual fact.
Some financial literacy programs in schools teach you to build your FICO score because that's been accepted as norm rather than actual fact. Instead, the approach should be teaching people to live on a budget, live on less than they make, be outlandishly generous, and save and invest in the power of compound interest. These things are agnostic to the banking community.
Teachers have been indoctrinated by the culture that this is the way you have to live - you're always going to have a car payment, you have to have a credit card, you can't be a student without a student loan. When you back it out and say the teaching is with an agenda, then you have to stop and go there's a villain in this story. Instead, we need to be teaching the basic premise of common sense.
Ramsey's high school curriculum is in about 48% of the high schools in America so far. Banks are not happy about that because they're teaching people not to borrow money.
There's a group of people called hope stealers who are saying that it's impossible to win now, that there are too many systemic problems, too many things that are broken in the culture and in the economy, that the little man can't get ahead. Yet Ramsey kept running into millionaires everywhere who were first generation, started with nothing, did not inherit their money. He started running into people who had followed the baby steps and became millionaires, which is why the book is called Baby Steps Millionaires.
The old Henry Ford line applies: If you think you can or you think you can't, you're probably right. You have to believe first. If you don't believe you can, you won't take the steps to do the hard work to be successful. Money is particularly weird in the spiritual area of belief because it will run from you if you don't believe. You won't do the sacrificial things. You won't live like no one else so that later you can live and give like no one else.
Only a crazy person would do something that they don't think is going to turn out. You have to believe first. The goal is to bring in emotional behavior, data of other people, and math to make you believe that you can do it.
We become who we hang around with. Your income is going to approximate theirs over time. Your physical condition will be influenced by theirs. If they take care of their bodies, you're going to take care of your body. If they have good marriages, you're going to have good marriages. You're even going to have an accent like they do. You need to get yourself in a community of people who are achievers who believe it can be done, who understand it's tough and will encourage you when you're having a hard time.
Growing up, Ramsey's parents were saying "You can do this," but a lot of the kids he ran around with had parents saying "The little man can't get ahead. You're always going to have a car payment. You're stuck." There's a group of people that declare themselves stuck, and there's also a smaller group within that same community that declare that it's possible to be free, possible to prosper. It's victims or victors, and anyone can make that choice.
The definition of a millionaire is not a Dave Ramsey definition. This is an accounting definition. Personal finance has been taught for decades. Assets minus liabilities equals net worth. What you own minus what you owe equals your net worth. When your net worth is $1 million or greater, you're a millionaire. It's not a feeling. It's a math formula. It's not a moral construct.
You can make a million dollars a year and not be a millionaire. You can make $30,000 a year and be a millionaire. It's a net worth balance sheet transaction, an accounting function.
Several years ago, the largest study of millionaires ever done in North America was conducted. Tom Stanley did a book in 1992 called The Millionaire Next Door with a sample size of 750 millionaires. The new study did 10,167 millionaires. 79% of America's millionaires inherited precisely zero. 8 out of 10. 5% more inherited a small amount like $1,500 or $5,000, which mathematically could not have possibly made them a millionaire. Another 5% inherited substantial money like $100,000 or $200,000 after they were already millionaires. So nine out of 10 of America's millionaires did not become millionaires because of an inheritance.
99% of millionaires are not household names. They're teachers, policemen, engineers. The number one career was engineer. Number two was accountant. Number three was teacher. Number four was executive. Number five was lawyer. Medical doctors made number six. These are all process people who believe in systems and processes.
The stuff being taught will not make you a billionaire. These are millionaires with one to ten million worth of net worth. About 83% of them had two things that showed up almost every time: they funded their 401k in good mutual funds and their Roth IRAs in good mutual funds over an extended period of time, 12 to 17 years. During that time, the average millionaire paid off their home in 10.2 years.
What most had was a $500,000 paid-for home and a million dollars in their retirement accounts. It's the power of compound interest, building up mutual funds, winning in your 401k, and just steady, steady, steady. Never stopping, never panicking when the market's down. It's boring, not sexy at all, but here you are sitting with a paid-for house and a million bucks.
Every one of these careers - engineer, accountant, teacher, executive, lawyer - are systems people. They believe in a set of principles, and when you follow those principles, you get a result. As you sow, so shall you reap. If you plant corn, don't be shocked when corn comes up. It's a cause and effect world that they live in. They believe in systems, they believe in processes.
Social media and the internet are creating generations of people who have the attention span of a gnat. They can't stick with anything. In order to do something of greatness, it requires steady application over a period of time. The old days of a craftsman going through years of apprenticeship to be world class at something are gone. Now people want to snap their fingers and instantaneously be able to do things.
The ability to delay pleasure is a sign of maturity. That's what grown-ups do. Children do what feels good. YOLO - you only live once quick. Instead of sacrificing to get a greater outcome, living like no one else so that later you can live and give like no one else. Short-term thinking and get-rich-quick has never worked at any time in the world as an ongoing provable sustainable process.
Generosity with these millionaires is a steady thing, like their savings is a steady thing. They're not trying to have one big event that says "Look at me, how generous I am." Instead, they're fairly quiet about it, almost absurdly quiet and anonymous about it, and they steadily give into something that they believe in. If they're Christian, they're giving a tithe at their local church. If they're Jewish, they might be tithing at their synagogue. Every religious background has a steady giving rhythm as part of its teaching because it's how you build character.
When you're giving, it's almost impossible to not become grateful. As you become grateful, the next thing that happens is you become more and more content. The more content you are in a totally discontented culture, the great advantage you have to build wealth.
If you throw the papers and you actually throw them and deliver them to the people's houses and you get paid the exact same as the guy who threw them away, that's not fair. You provided a much more service to the community. You had integrity. You didn't steal. And the guy who threw them away took someone else's papers, they weren't his, and he threw them away. That's stealing. And he didn't follow through on his promise. And he was getting paid for a service he didn't even attempt to do. That's also stealing. So his lack of integrity and lack of service in the marketplace. And to say that those two people should be paid the same is an immoral statement. Equal is not fair. It would not be fair for that guy to get the same money over time as you got.
Dave Ramsey would never propose that two people doing the exact same thing and providing the exact same level of service somehow got different because of their skin color or their sex or something like that. No. They've got folks of every background, every ethnic origin, and everything else on their leadership team. And they're completely blind to all that. All they want to know inside Ramsey is did you do the job? And if you did the job, you get the money. And that's how that works. And so that's the only measure.
To say that we're going to spread it out across the people who did the work, didn't do the work, who plowed the field or didn't plow the field, who showed up when the storm came through and got the tree out of the road, the other one just sat at home and watched and played some kind of game on the TV or something. That's just communism is what it is at its core. It's an economic system. It's not name calling. This idea that things are equal. So we have to eliminate that. Number one. Then once we eliminate that, then we start to understand what Rabbi Lapen's an Orthodox Jewish rabbi. He says that money comes to people who serve. That when you serve your customers give you certificates of appreciation with president's faces on them.
This idea that evil people prosper. No they the percentage of evil people among the wealthy is about the same percentage of evil people among the poor because again money makes you more of what you already are. You're magnified. And so here's the thing you think about if you got a guy that works on cars. He has an auto repair shop. And you go in there and he tinkers around on the car. He says, "That'll be $150." And you drive away and the next day your car breaks down again. You come back in there, you go, "Hey, I gave you $150. You didn't fix my car." He goes, "I know, but it'll be another $150." You say, "I'm not giving you another $150." And you go back. Finally, you go, "Okay, this guy's a crook." Okay. Or he's incompetent. One of the two. He doesn't know how to fix my car. Now, what do you do? Do you keep going there and giving the guy money? Obviously not. No, you no more than that. You go tell everyone you know, "This guy's a crook. Don't do business with him." Now, does that guy prosper at the end of the story? Of course not. He goes out of business. Over time, the marketplace will punish him for his crookedness.
Take the guy next door who's got an auto repair place. You go in there, he looks under the hood and he goes, "Oh, there it is." And he goes, "You're okay. What do I owe you?" "Nothing. Just remember me when your car really breaks cuz I just fixed it. It's no big deal." And you drive away going, "I found a guy who fixed my car for free and he actually is honest. This is a unicorn. I'm going to tell everyone about this guy." And then this guy, you know, we visit this guy now 20 years later. He's got a franchise operation. He's got this color of store fixing cars in 56 cities across America. He's worth $8 million. And now he's evil. What? That's absurd. The line of thinking here, the critical thinking skills that get you to that are non-existent. It's impossible to be a crook and prosper in a free marketplace long term or to use crookedness as a method of wealth building because it actually works against you.
Money is amoral. It's not about money. It doesn't have morals. It's about the human being. And when it touches that human, it reflects who they are. Dave knows evil people that are rich, but he knows a lot more that are unbelievably kind, generous, grateful. They got more time for you than and they'll do anything for any. They're just unbelievable humans. And that's the one he knows a lot more of those than he does crooks.
The best financial advice Dave has ever heard, received, or given is: Be intentional.
The worst financial advice Dave has ever received or heard is: You can borrow your way into wealth.
The best investment or spending Dave has ever done in his life is: Giving.
Dave's biggest financial mistake of an investment or expenditure was: Going deeply in debt to build wealth.
If Dave could make one law that everyone in the world had to follow, it would be: He would require them to be generous.
When people say that they want to build confidence. The reason why it's so difficult to do that is because confidence is it's an output. It's not an input. And so when you think about it you don't get confidence by trying to be confident. Often times confidence comes after you are competent in something. And so for the speaker, they didn't realize that. In fact, when they were 19 and they were overweight and they were drinking and they were doing drugs and they were just like completely spiraling, they remember they literally had a mirror in their bathroom and they had affirmations written and they would be saying these affirmations to themselves. They'd be like, "I'm beautiful. I can do this. I work hard. I have money. I'm wealthy." And they would read them and they remember just thinking like none of this is true. And it felt really weird to them because they kept thinking like this is supposed to work. This is what I'm supposed to do. And then like nothing would happen. And they were like, why am I not feeling confident? They were insanely insecure. And by the way, like people that know them very well will say like you still are quite insecure. Like it's in different areas. They kept waiting to feel ready. And then they realized you don't ever feel ready until the second time that you do something. And that's because in order to feel confident, which is feeling ready in their opinion, you have to build competence in something. And the only way that you build competence is by building evidence for yourself to understand that you can actually do the thing. In order to do that, you have to pay the price, which is by having never done the thing before. And so, it wasn't until they said, "I'm so sick of like being in my head trying to think my way into being confident and said, I need to act my way into confidence. How would I do that? Okay. Well, I have to get competent at something. Well, at that point in their life, you know, they were like, I'm not really that good at anything. They weren't really that skilled at anything. So, it would also make sense that you're not competent if you don't have that many skills, right? And so, they learned sales. That was the first thing they learned. They moved across the country. They didn't know anybody. They had $5,000 and they were like, I'm going to learn how to do this. They were also viscerally opposed to the thought of sales, but they were like, I need to understand this. I need to understand these core skills, otherwise I'm never going to be able to build a business. And so, they drove out to California. They found the closest gym within walking distance. They applied to all of them, right? And then they took the one that was the absolute closest and they got the job. And they remember they started and they were like, "Cool. So you understand how to help people lose weight and how to help people get healthy, but like you need to know how to market and sell yourself." And so that meant like walking to Whole Foods and trying to get solicit people at the Whole Foods. That meant like when somebody was doing cardio, going up to them on the machine being like, "Do you need help?" And they remember the first time they walked up to a lady on the treadmill, it was the first person they ever walked up to them. They're telling their boss at this time. They're like, "Dude, I don't know what I'm doing." He's like, "Listen, it's not going to be that bad. What's she going to say?" The first person they walk up to, of course, she looks at them and she was like, "Off." And they were like, "Ah." And they remember they ran into the bathroom and they sat on the toilet in Whole Foods. And they were like, they literally think they're going to have a panic attack. Like they felt so bad. They felt like their stomach was in their throat. They remember telling themselves, they were like, "You can't let yourself down. You've got to make this worth it. Like, you drove out here. You quit everything. You told everyone that you were going to do this. You told everyone you become an entrepreneur and have a business." So, they were like, "Okay, I'm going to focus on what I can do." And so, they focused on how do I get as many nos as possible. And through getting all the nos and being rejected and seeing that they could handle it, which they were terrified of rejection prior to this, by the way, like bullied in school, not cool, like didn't have that many friends, like not cute, like it was just the whole thing. That was what built their confidence. And they think that so often we think that the thing that's going to make us confident is the thing that feels good. But what's good for us often feels bad in the moment. And what feels good in the moment is often bad for us in the long term. And that's really like the biggest lesson they learned. And then they realized they were like all the times that they built the most confidence in themselves, they weren't focused on being confident. They were focused on becoming the best version of themselves they could be, which meant that they were becoming more competent and then by consequence they became confident. They never thought about they got to get more confident after they realized they were like it just happens naturally if you do these things.
So often, you know, people come to them and they're like, they just want them to tell them the marketing hack or the sales hack or and they're like, listen, that's where they started. They started in sales and marketing. The reason they talk about everything else they talk about is because they realized that that's not what ends businesses. So, they'll give you a story to demonstrate this. They had a company that they worked with and that company was like crazy growth. Like they started with them, they were doing like 2 million a year. Within 3 years that company is doing 90 million a year, crushing it. Absolutely absurd. They get a threat from a competitor. That competitor starts to point out things in their marketing on their website, all stuff like of all these things that like they're going to try and take them down for and they're going to copy and their competitors start copying other stuff and then threatening other things. Their competitor then, you know, serves them with like a lawsuit and is like, "Hey, I'm going to sue you for this thing." And they're like, "Dude, they have no grounds. I was like, Don't even worry about it." And they know cuz like when they had their first lawsuit, they're like up at night, you know, like, "Oh my gosh, this is so scary." And nothing happened. So they get into this lawsuit within 6 months of the lawsuit being served, the company was at zero. The company was not at zero because of the lawsuit. In fact, the lawsuit ended and they won. The company is at zero because the founder, she was so unstable that she ended up shutting down the business because she couldn't handle it anymore. And they remember being on the phone with her and she literally said, she gives them all these reasons, right? It's the marketing, it's the sales, it's this that they're giving me, it's this piece that they're serving me. And it all came down to they were like, but you could do this, but you could do that, but we can do this. Like, please trust me. This is why I'm your partner because I can get you through this. Like they've been in many lawsuits. And she was like, they just can't handle it. And it was like in that moment they remember they were like the number one reason that people cannot grow a business and that they don't succeed is because they cannot manage their own mind. They cannot manage their mind and they cannot manage their emotions. And they've just seen it so many times like the market doesn't put you out of business. You put you out of business. The same thing happened during COVID. They mean, they had thousands at that time of customers that were business owners that they worked with. And they saw the amount of people that COVID didn't end their business. Their inability to manage their emotions during COVID is what ended their business because eventually they would just throw in the towel and they would make up some excuse outside of themselves. It was the market, it was the lawsuit, it was the fact that they told us they had to be 6 feet apart, whatever it might be. And it always came down to the fact that they didn't want to tolerate those feelings anymore. They had a low frustration tolerance. They couldn't tolerate the feelings of uncertainty. They couldn't tolerate the feelings of frustration. They couldn't tolerate the feelings of unpredictability. And they have just seen every big business that they've seen go down, which they've seen they would say five more businesses besides the one they just told you about. It was always because the founder didn't have enough emotional management. They could not manage themselves emotionally during those turmoil, like those situations that felt like turmoil. And they will tell you, you know, there was a time where they were in so much pain they could, you know, they were working from the couch every day. They had four lawsuits on their plate. They were having issues with some stuff personally with their family. And in their business, they were also, they had 12 direct reports. They had four new people they just hired. And they were performing 3 days a week. And the only reason that they were able to do that was they were like, they are going to double down on making sure that they can manage this. And it was the hardest season of their life, but they got through it and they're better for it. That's what breaks most people. It's when everything collides at once. And then how do they deal with the uncertainty? How do they deal with the frustration, the anger, the anxiety? And then they just say they find some reason outside of themselves and they point to it and say that's why it didn't work every time.
There's no difference in the person. They think that's like the biggest fallacy that they see with people like you're disciplined. It's like no, you know how to build discipline. Discipline is a system. And so the easiest way to explain it is that if you want to be disciplined, make it easier to do the things that you want to do to achieve your goals and harder to do the things that work against your goals. So, a great example is this. People are like, "I'm just not disciplined." You know, like, "I'm eating ice cream every night. I just can't seem to lose weight." Well, discipline, if we look at it like a system, you have a prompt in your house. You have ice cream in your refrigerator. That's a literal trigger for you to eat the ice cream. So, let's remove it and then let's insert, they don't know, vegetable sticks or they wouldn't do that, but like they would do like a hot cocoa, diet hot cocoa. That's a good one for them. And they would put it in the same place. And so it's interesting because like when they went to lose weight, they didn't say to themselves like, "Oh, you're a piece of because you can't lose weight." They were like, "Oh, I don't have good systems in place. How do I make it as easy as possible for me to do the steps that I need to do to lose weight? How do I make it as easy as possible for me not to drink? How do I make it so? Okay, let's look up each of those. Easy as possible not to drink. Easiest thing they did, they lived with six people who all drank. What did they do? Move out." Like it's so simple, but it's like half of the trigger like they would say 50% of their desire to drink went away immediately because they were around people doing it all the time and it was a constant prompt. Hey, remember you like drinking, drink, drink, drink, drink. Prompting them all day. Now, on the other hand, when they were like, okay, they're trying to lose weight. The first thing they did, they did two things. They were like, they're getting rid of all the drunk food in their house. The second thing, they deleted and got rid of anything on their phone that they could order food with because what are the two ways that they're going to get junk food? It's either be in their house or they're gonna order it. Now, if they want junk food, they're going to drive. Oh my god. Now, there's like so many reasons why they're not going to do that. That doesn't mean they think a lot of people think in order to be disciplined, it means that you have more desire. No, their desire for that ice cream was hot. But there was so much friction to get it that it's just like, ah, they guess they'll just deal with the desire. And most people have it working the opposite direction because a lot of people say they're like, you know, they look at discipline and they think discipline is just doing things consistently to get you to what you want. Lots of people do things consistently to not get what they want. You consistently eat the ice cream. You consistently don't go to the gym. You consistently. So, you have systems set up to make it easy for you to not achieve your goals. And so, we have to switch those systems. That's it. It's a terrible thing that so many people like, you're not disciplined. No, you don't have the skill of building disciplined systems around you. It's such a different way to look at it. And some of these things are very easy. Like if you were to look at their phone, you know, when they open their phone in the morning, the first thing that they have is that they have a notification for insight timer, which they use. And it says like time to meditate. They have meditated. It's now 179 days in a row. And that's when they first started. They're going to meditate every day at this point in their life. You know, the second thing they have is that they have their My Fitness Pal and it pops up and they have a prompt on it where they put a little prompt for every time they eat where it comes up on their phone as a reminder from their iPhone and it says log your food. They don't. Is that discipline or is it their environment reminding them to do something? Memory is a liability. A lot of people think they need to remember. They're going to remember that they want to lose weight and that they want to be an amazing girlfriend and that they want to build a business. And their memory and desire should create the result. That is a fallacy. There are going to be so many things that take your attention all day. So, how are you going to build in systems that grab your attention? Just triggers. It's like it could be a piece of paper, it could be a note you write for yourself, it could be not having the food in the house, it could be a friend that calls you, a text you have. We have to make it easier to achieve our goals, not harder.
The first thing they would say is that you've got to show them the meat on the bone. Nobody wants a bone that's been chewed to bits that looks like a piece of and there's no meat left on it. So the first thing that you've got to show people is where's the meat left on the bone? So for an example, when they were selling gym launch, they said you know we've tapped this piece of the market. They have small group class gyms. They haven't tapped big box gyms, yoga studios, pilates studios, crossfit even. They haven't tapped any of that. And so then they said, what's the size of that? How much meat is left on the bone there? That's the first thing is that nobody wants to buy a business that has run out of opportunity. And a lot of people unfortunately come to investors too late when they have run out of opportunity. That's the first piece is like where do you have opportunity meat on the bone?
The second piece is when you're pitching somebody to invest in your business, they would say that you are selling them on the team rather than yourself. They think that when people look at investing in a business, specifically themselves, it's like great if it's an amazing founder, but you're one person and if you die, get hit by a car, anything happens, then like who's behind you? And so they're like, they want to know that the team has got this business, not just the founder. And so you're going to have your team on the calls, have your team in the pitches, have your team be able to do the pitch. They did that when they were selling their company. It's like they were literally there pitching the company cuz they were like you think that they run this business and they're in the day-to-day watch the people who actually are like they'll pitch the company for them. It's like what's a bigger move than that? So that's the second piece.
And then the third piece probably specific to them. But they think it is the way in which you go about the negotiation that tells them more about the founder and about the company than anything. And so if they were trying to if they were an entrepreneur trying to get someone to invest a million dollars in them, they would demonstrate through the negotiation process of trying to get the money the type of person they were. Because at the end of the day, you pick the jockey, not the horse. A great entrepreneur can turn a shitty company into a great company and a shitty entrepreneur can turn an amazing company into a piece of
A great entrepreneur can turn a shitty company into a great company and a shitty entrepreneur can turn an amazing company into a piece of garbage. When evaluating entrepreneurs, the key is observing how they show up during the investment process. This includes whether they arrive early or late to calls, whether they show up well, and whether they are prepared. People who call in while on the road or say "Sorry, I'm on the road right now" demonstrate they don't have enough time to sit down and take the call seriously. This behavior indicates how seriously they take the investment opportunity.
This reveals a lot about how someone will treat others. If an entrepreneur doesn't treat potential investors well when they're trying to get money, it reflects how they likely treat their team, employees, and clients.
Getting to First $100K in Revenue
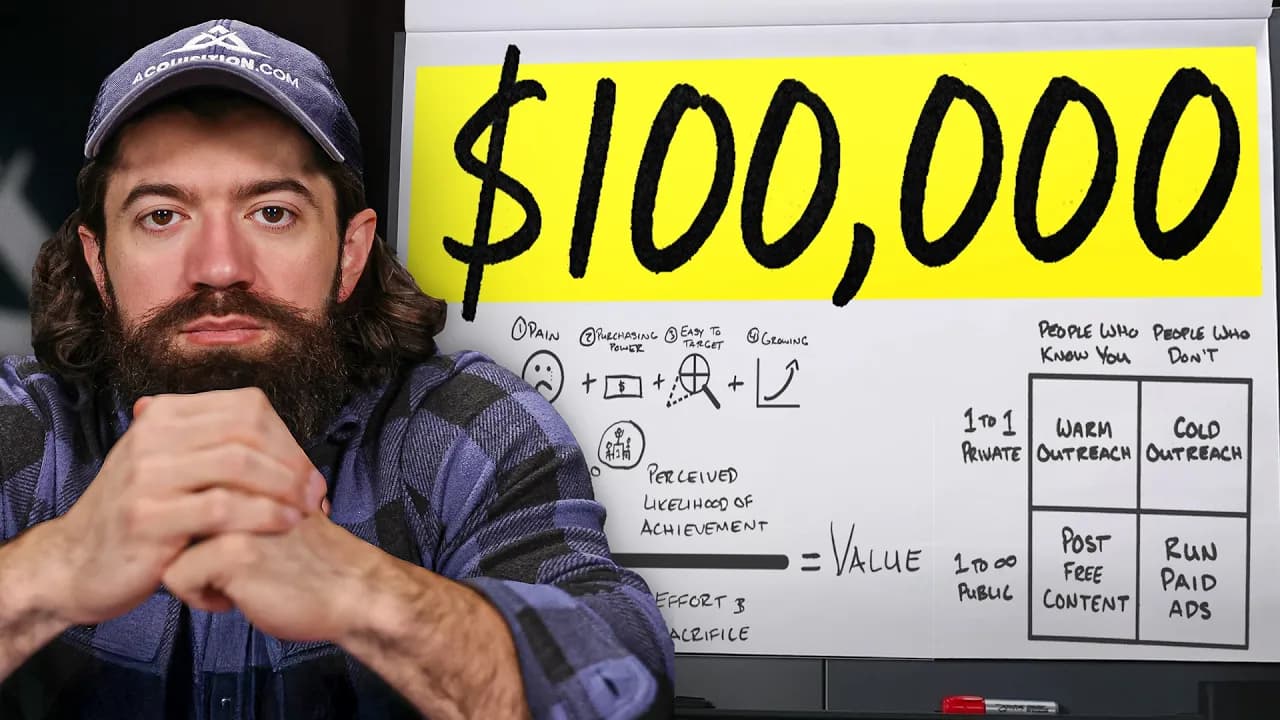
To reach the first $100K, focus on selling one thing to one person through one channel. Many entrepreneurs are scattered, working with multiple client types like hairdressers, coaches, and fitness professionals simultaneously. The approach requires one avatar, one channel, and one sales process. Everything must remain super simple to reach this milestone.
Getting to First $1 Million in Revenue
The approach is similar to reaching $100K - maintaining one channel, one avatar, one way of selling, and one product. The critical difference is developing consistency. While $100K can be achieved with inconsistent effort - having a good week followed by a bad week, turning marketing on and off, posting content sporadically - reaching $1 million requires consistent execution. This means being able to take 20 sales calls a week, every week, not just three weeks but four weeks a month. Consistency acts as the amplifier to reach this level.
Getting to $10 Million in Revenue
To reach $10 million, entrepreneurs must get other people to be consistent for them. This allows building the next product tier, as companies realize they need different products for different customer segments. The entrepreneur cannot continue doing everything that got them to the million or seven-figure mark while building new products and channels. They must delegate consistency to others so they can build the backend and branch out to new channels.
Patience
Patience is the rarest trait seen in people in their 20s. Across teams with 30 to 75 people in their 20s, the number one trait of those who succeed is patience. This includes being able to do boring work, focus on something without distraction, avoid shiny object syndrome, and not be distracted by what friends are doing to make quick money online. Patience pays significant dividends.
The Jacob Example
Jacob, a director of sales at Acquisition.com who runs one of the largest teams, joined at age 16 and is now 23. When told he needed to just be an SDR and call phones, he never asked when he would move up or advance. He got ruthlessly good at the skill in front of him. His patience and focus on becoming excellent where he was at led to faster expertise development. The irony is that when people are distracted trying to move up quickly, they don't acquire the level of expertise needed to advance.
Patience Encompasses Multiple Skills
Patience includes focus, the ability to tolerate boredom, and the ability to tolerate distractions. Acquiring these skills in the 20s creates significant advantages. The lack of patience is the number one reason people in their 20s are not succeeding.
Success needs reframing and clarification. The pursuit of buying the New York Jets isn't about needing the team but about the fun of the game and process over trophies. Trophies shouldn't be used to close gaps of insecurity. Success should be redefined so that someone who is genuinely happy, even without making the same dollars as others in the room, is recognized as the winner.
The Accountability Problem
The lack of accountability is leading to significant unhappiness. Life becomes much better when people take ownership and say "This was my fault." This puts individuals in control. People decide what they consume, what they believe, who they surround themselves with, and what they put out into the world. Everyone wants to blame external factors like algorithms, but accountability means recognizing that apps can be deleted and choices can be made.
The most worthy pursuit is finding the continuous balance between being selfish and selfless, and refining that skill set. This involves being wildly gifted at helping other people while being comfortable feeding personal interests. The balance beam gets thinner over time, but the energy from entrepreneurship allows deployment in positive ways at scale.
The first thing to build is centering decisions around what is important personally, never sacrificing ambition. People need to be very honest and open about what they need and what they're looking for. Focus on what can be done right now and be excellent in whatever is being done currently. Excellence at something propels people into the unimaginable and gets them recognized for skills outside their current perception.
Being magnetic comes from being really good at something. Even in a casual restaurant, exceptional service with great recommendations and energy attracts attention and opportunities. Being excellent even at what is hated prepares someone to be exceptional at what they love.
The three most important words for career acceleration are "I'll do that." Rather than following passion, find what you're good at and what lights you up. Identify what gives energy versus what takes energy away. Purpose emerges from finding what gives energy and what natural skills lean toward, rather than searching for purpose directly.
Competence builds confidence. Following what you're good at means getting better whether things are going well or not, rather than losing passion when things get hard. Focus is a force multiplier - going deep on one thing rather than spreading thin leads to unbelievable unlocks. Overnight success stories aren't true, and it doesn't get easier with more success - it gets more difficult.
Start by putting yourself out there. Test ideas on smaller platforms like YouTube or Instagram versions before going big. Take the best pieces of an idea and try them in small ways that can be done immediately. If everything is figured out but waiting for the perfect opportunity, that day may never come. Starting allows testing, learning, failing, iterating, and starting again.
Time management has evolved from chasing freedom of dollar to freedom of time. Even with financial success, everyone has the same amount of time. The focus should be on doing $1,000 tasks rather than $10 tasks. For some, cooking with family is a $1,000 task that shouldn't be outsourced, while other responsibilities can be delegated.
The Do, Delegate, Delete Process
Every couple weeks, conduct a time audit using the process of do, delegate, delete. Understanding where you want to go allows working backwards to determine the three most important things. As startups, the temptation is to do all things, but focus must be on the critical few.
"Leave everyone and everything better than you found."
"Whatever you want and whatever you're thinking about doing in your life, the most important thing is to focus on what you're doing and what you can do right now. Be excellent in whatever it is that you're doing right now."
The speaker applies the rule of three to everything, stating they can't remember more than three things. They set three goals for the quarter or year and work backwards from those goals. Everything else becomes a delete or no. Each day they identify their needle movers—the three most important things that move them toward their goals. They emphasize getting comfortable with saying no and not being the one to do everything.
Sira was 26 years old with no money in her bank account when she started STAX. She was working for a financial services company and was the first person in her family to graduate college. Her parents immigrated from Karachi, Pakistan, and she was born in Chicago as first generation. The family moved to Texas, and she attended 10 different schools in 12 years.
Her parents emphasized the pursuit of the American dream and education, which is deeply valued in Indian and Pakistani culture. She grew up as the firstborn eldest daughter in a Muslim household where she never felt defined by her gender—she was simply the eldest kid who got to do everything first. Her father would wake her and her brother up at 4 AM every morning, calling her "Sny" and saying "You have it," providing constant confidence and support.
Sira attended University of Florida where she studied abroad and experienced championships during her four years. It wasn't until entering the workforce that she noticed gender differences. At three different companies she worked for, women were only in customer support or admin roles, with no women in technology or other positions. This was the first time she noticed being different and began experiencing negative self-talk in her early 20s.
Sira was considered a bad employee because she challenged the status quo. She developed an idea for a subscription-based processing system but was laughed out of the room by her male bosses. After returning home disappointed, her father suggested she start the company herself. When she asked where to find "Mr. Visa" at age 25, he simply said "you'll figure it out." She moved back into her parents' house, and her father gave her six months before returning to pursue her MBA.
She sold the first 100 customers out of the trunk of her car, carrying payment terminals to shopping plazas. Her daily goal was simply to get one person to say yes.
The transition between business stages requires complete change at each level. Going from zero to six figures is different from six to seven figures, which differs from seven to eight figures. Everything breaks at each stage—systems break, people break—because it's supposed to break under the pressure of growth. The speaker emphasizes that doing the same thing expecting different results is insanity.
Three key elements must be scaled: people, process, and profit. Most companies beyond million-dollar revenue validation have multiple revenue lines. STAX shifted from acquiring small businesses to an enterprise strategy, selling directly to banks and enterprise customers first before small businesses—this took seven years to unlock.
The one constant throughout scaling was the company's values. Sira wanted to see the company through to exit and worked intentionally to be the best CEO possible. The culture was built on a value system, with "one team" being central—derived from her relationship with her brother, expressed as "one team, one dream." Core values don't change but evolve, remaining grounded while the playbook shifts.
The company was originally named Fat Merchant when founded at age 25, which Sira recognized as a hundred-million-dollar company name, while STAX represented the billion-dollar vision. She had to become comfortable making pivots and changes despite it being her company.
The freedom formula consists of three elements: freedom of dollar (financial freedom for security), freedom of time, and freedom of impact. Financial freedom doesn't require having all money in the bank but enough to feel secure.
To avoid loneliness at the top, surround yourself with real friends who also feel lonely in their fields. Maintain a small but meaningful circle.
If creating one law everyone must follow, it would be leading with kindness. Before saying anything negative, do it with extra love—love on each other and love on ourselves to make the world perfect.
Keep Jay Shetty Podcast in your library
Save the videos and channels worth coming back to, and find them again in one place.